Key Takeaways
- Understanding key annuity features and risks is crucial when planning safer retirement income as a senior.
- Evaluating alternatives and asking strategic questions can strengthen retirement income protection.
Did you know many retirees worry their savings won’t last? Exploring ways to support steady retirement income is more important than ever. Knowing how annuities work—and how to evaluate their potential benefits—can help you make more informed decisions for your financial future.
What Are Annuity Benefits for Seniors?
Basic annuity concepts
An annuity is a contract between you and an insurance company where you provide a lump sum, or a series of payments, in exchange for a stream of income in retirement. The primary appeal of annuities is their promise of regular payments over a specified period—or even for life—helping reduce the fear of outliving your savings. Annuities aren’t one-size-fits-all; their structure and benefits can vary significantly, affecting how well they align with your retirement goals.
Types most often used by seniors
Many seniors most often use immediate annuities, fixed annuities, and, occasionally, indexed annuities. Immediate annuities start providing income shortly after the initial investment. Fixed annuities pay a guaranteed amount for a set term. Indexed annuities, meanwhile, may offer the potential for higher returns based on the performance of a particular market index, while typically providing some level of principal protection. Each type comes with its own blend of potential benefits, limitations, and complexity.
Why Consider Annuities for Retirement?
Role in stable retirement income
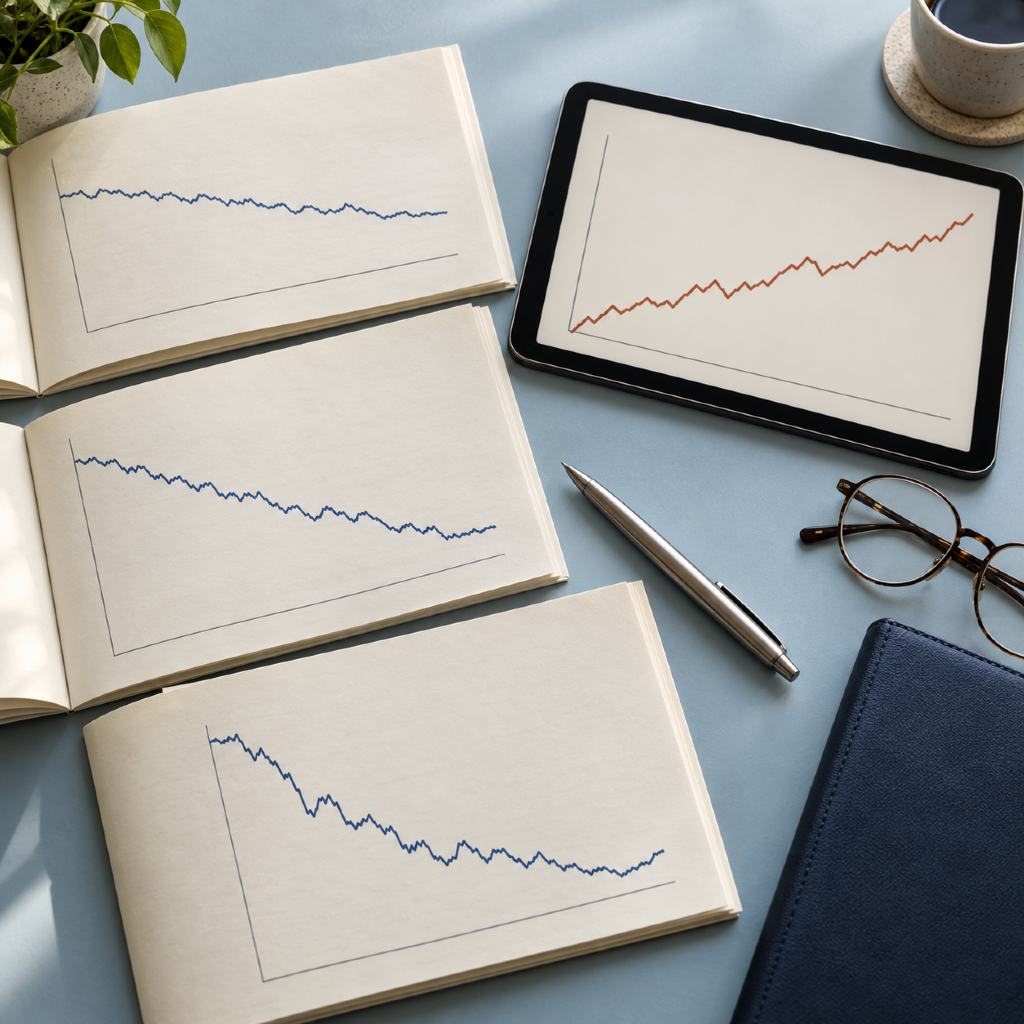
Annuities’ primary role in retirement planning is providing reliable, predictable income. This can help smooth out the ups and downs you might experience with market-tied investment portfolios, especially during prolonged downturns or periods of volatility. For some, the psychological comfort of a defined income stream is as valuable as the payments themselves.
Alternative solutions to market risk
Market risk—the possibility that your investments will decrease in value due to changes in the financial markets—looms large for many retirees. Annuities can counterbalance this risk, reducing exposure to fluctuations and helping shield your core retirement income from potential downturns. They’re just one tool among many for managing market risk, with others including diversified portfolios, bond ladders, and government-backed securities.
How Do Annuities Support Income Protection?
Strategies for stable income streams
Annuities can be structured to provide regular payments for life or for a set period, reducing reliance on other assets subject to market volatility. Choosing a payout option that matches your anticipated expenses can help ensure your essential needs are covered, no matter how the market performs. Some annuities also offer spousal benefits or survivors’ options to continue payments to a loved one if you pass away.
How principal protection can work
Many seniors are drawn to annuities that advertise principal protection. This means your original investment can be shielded from losses due to market declines, although terms and limits apply. Read the fine print: some products guarantee you won’t lose your principal if you follow the contract rules, while others may expose you to risks or fees if you withdraw funds early or don’t follow the policy exactly.
What Should Seniors Look For?
Key factors to compare
When evaluating annuities, compare contract features, payout options, expenses, and surrender charges. Key factors include the payout period, how income amounts are determined, and whether beneficiaries are an option. Be sure to understand all costs, including administrative fees, management charges, and early-withdrawal penalties. Also, compare how different annuities address inflation protection and liquidity needs.
Questions to ask before committing
Before committing to an annuity, ask:
- What is the surrender period, and how much are the penalties if you need access to your money?
- Are there fees that could impact your returns?
- How is the income amount calculated, and can it be adjusted, or is it fixed?
- What happens to the contract if you (or your spouse) pass away?
- Is inflation protection included?
- Does this annuity fit my broader retirement plan and needs?
Getting clarity now can help you avoid future surprises.
How to Evaluate Annuity Features Safely
Understanding terms and conditions
Carefully reviewing the terms and conditions of any annuity contract is essential. Pay close attention to how payouts are structured, whether there are conditions for receiving guaranteed income, and what situations could change your agreement. Look for transparency in how information is presented, and ask for clarification on anything that’s unclear.
Evaluating risk and suitability
Suitability means assessing whether a particular annuity aligns with your financial goals, risk tolerance, time horizon, and liquidity needs. Ask yourself if the annuity addresses your main concerns, such as guaranteed income, legacy planning, or principal preservation. It’s usually wise to consult a qualified, unbiased financial professional to clarify things and confirm your understanding, especially if the product seems complex. Remember: not every annuity is ideal for every situation.
Are There Downsides to Annuities?
Potential limitations to consider
While annuities can offer security, they also have important limitations. These may include limited liquidity (making it hard to access your money quickly), potential early-withdrawal penalties, fees that reduce overall returns, and the possibility that your payments won’t keep up with inflation. Some annuities are more complex than they appear, so it’s essential to understand exactly how they work before committing.
Ways to avoid common pitfalls
To sidestep common mistakes:
- Avoid locking all your savings into a single annuity.
- Make sure you understand the surrender schedule and associated fees.
- Review whether the annuity meets your specific goals for accessibility and legacy planning.
- Don’t be swayed by sales pitches; focus instead on unbiased education and transparency.
Taking the time to review contracts and ask tough questions can help you avoid regret down the road.
What Alternatives Exist for Safer Income?
Other principal protection strategies
Other approaches can support a steady income in retirement while preserving principal. Certificates of deposit (CDs), Treasury securities, and laddered bond portfolios are all common strategies used for generating stable cash flows while reducing the risk of major losses. Diversifying across income-producing assets can further spread risk and provide more flexibility.
How annuities compare with alternatives
Compared with alternatives, annuities offer guaranteed income streams from an insurance provider but usually come with reduced liquidity and potentially higher fees. Other strategies may not guarantee income for life, but they can offer more flexibility or access to funds. Each approach has its trade-offs, so it’s vital to consider which priorities—flexibility, stability, or potential growth—matter most for your personal situation.