Key Takeaways
- Understanding interest rate risk can help you make more informed decisions about bonds and retirement planning.
- Proactive risk management techniques like diversification and laddering can help stabilize your portfolio.
Most retirees underestimate bond risk—learn how changes in interest rates can quietly affect your savings and discover strategies to help protect your future income. If you want to maintain stable retirement savings, understanding how interest rate movements affect bonds is essential. This Q&A guide breaks down what you need to know to feel more financially secure.
What Is Interest Rate Risk?
When you own bonds, interest rate risk is the possibility that changes in prevailing rates could impact your bond values. This fundamental risk is always present, regardless of the type of bond or the timing of your purchase.
How Bonds React to Rate Changes
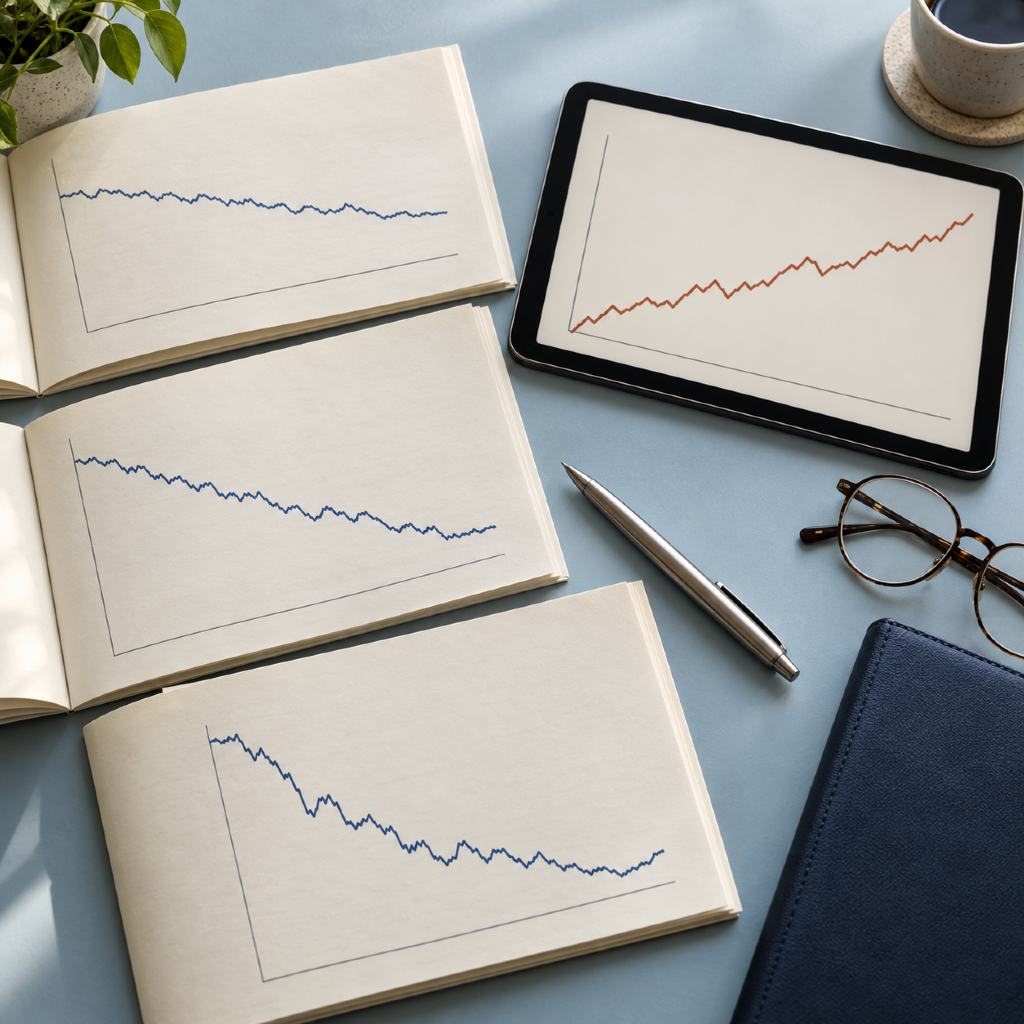
Bonds generally move opposite to interest rates. When interest rates rise, existing bonds may lose value because their fixed coupons become less attractive than newly issued bonds with higher payments. Conversely, when rates fall, your bonds may increase in value if their interest payments exceed current market offerings. This seesaw effect is a core characteristic of bond investing.
Common Types of Rate Risk
Interest rate risk can come in several forms:
- Market risk: The broad risk that overall market interest rates will move, affecting many bonds at once.
- Reinvestment risk: If interest rates fall, you might have to reinvest maturing bonds at lower rates, potentially earning less income.
- Call risk: Certain bonds can be repaid early by the issuer if rates decline, causing you to reinvest at those new, lower rates.
Each of these risks can shape your retirement outcomes, so awareness and understanding are crucial.
Why Is Interest Rate Risk Important?
This risk matters most for those prioritizing income stability and principal preservation in retirement. Interest rate shifts can affect your confidence in steady cash flow and overall account value.
Impact on Retirement Portfolios
For many retirees, bonds serve as a cornerstone for generating predictable income. However, rising interest rates mean the market value of existing bonds can drop—potentially lowering your portfolio’s total worth if you need to sell before maturity. This matters a lot if you rely on your investments to fund everyday expenses.
Long-Term Planning Considerations
Over multiple years, reinvesting at lower (or higher) rates can either hinder or help your plans through compounding. Failing to account for interest rate shifts can throw off income estimates and increase uncertainty in later years. That’s why you should regularly review your approach and adjust as needed as rate environments change.
How Can You Manage Interest Rate Risk?
While you can’t control the direction of rates, you can use specific strategies to help reduce the effects of rate movement on your portfolio. Two widely used approaches—diversification and laddering—can help support a more stable retirement outcome.
Diversification as a Safety Tool
Spreading your investments across bond types, sectors, and maturities can reduce overall risk. For example, maintaining a mix of short-term and intermediate-term bonds may limit the pain when rates move quickly in either direction. Pairing bonds with other income-generating assets, or using cash equivalents for short-term needs, can further strengthen your safety net. The goal is to avoid having all your investments respond to rate changes in the same way.
Laddering Bond Strategies
Laddering involves buying multiple bonds that mature at different times. Imagine your portfolio as a staircase, where each “step” is a bond with a different maturity date. When a bond matures, you can reinvest the funds at prevailing rates. This helps “average out” your exposure, potentially smoothing out the impact of rate shifts over time. Laddering adds flexibility and lets portions of your portfolio adapt as interest rates fluctuate.
What Happens When Rates Rise?
Understanding what to expect when interest rates increase can help you stay ahead of sudden changes. Rate increases are a normal part of economic cycles, but your portfolio’s response isn’t always straightforward.
Effects on Bond Values
When rates rise, existing bond prices typically fall. New bonds offer more attractive yields, so current bondholders may see lower resale values for their existing bonds. However, if you plan to hold bonds to maturity, you will typically still receive the original principal back (assuming the issuer remains solvent). The main impact is on the “market value” of your holdings and any income reinvestment opportunities.
Portfolio Adjustment Ideas
If interest rates rise, you can re-evaluate the types and maturities of bonds in your portfolio. Shortening your average bond duration or allocating a portion of your portfolio to cash or floating-rate instruments may help reduce sensitivity to further rate increases. Regular reviews with a financial professional can help you adapt as economic conditions change, with the goal of preserving both income and stability over the long run.
Does Bond Duration Matter for Retirees?
Bond duration is a valuable metric to assess how sensitive your bonds are to rate fluctuations. For those in retirement or planning retirement income, duration can significantly influence risk management decisions.
Understanding Duration Concepts
Duration measures how much a bond’s value will change in response to interest rate shifts. In general, shorter-duration bonds are less affected by rising rates. Longer-duration bonds see more dramatic value changes and can pose more risk if you need to sell soon. Knowing your holdings’ duration is a smart way to gauge overall exposure.
Aligning Duration With Financial Goals
Retirees often match bond durations to upcoming spending needs, aiming for maturities that align with planned withdrawals. By doing this, you help “lock in” returns for when you expect to need the cash, potentially reducing unwanted surprises. This approach also supports reliable income distribution strategies over time.
Frequently Asked Questions About Bond Risk
How Often Should I Review Bonds?
Review your bond holdings at least annually, or after significant economic events. Regular reviews help keep your portfolio aligned with your risk tolerance, time horizon, and income needs, so you can adapt to changes in the market and your life circumstances.
Are Bonds Still Safe for Retirement?
While bonds typically have less volatility than stocks, they still carry risk—especially as interest rates shift. With prudent management, diversification, and proper planning, bonds can still play a valuable role in supporting stable retirement income.