Key Takeaways
- A home repairs sinking fund offers a structured, proactive way to protect retirement income from unexpected repair costs.
- Safe funding strategies focus on protecting principal, maintaining liquidity, and stable diversification to preserve financial security.
Managing home repairs can become an unexpected financial challenge in retirement. A dedicated sinking fund helps you cover these costs without jeopardizing your income security. Let’s walk through why this planning step can be essential and how you can make it work confidently and safely.
What Is a Home Repairs Sinking Fund?
Definition and purpose
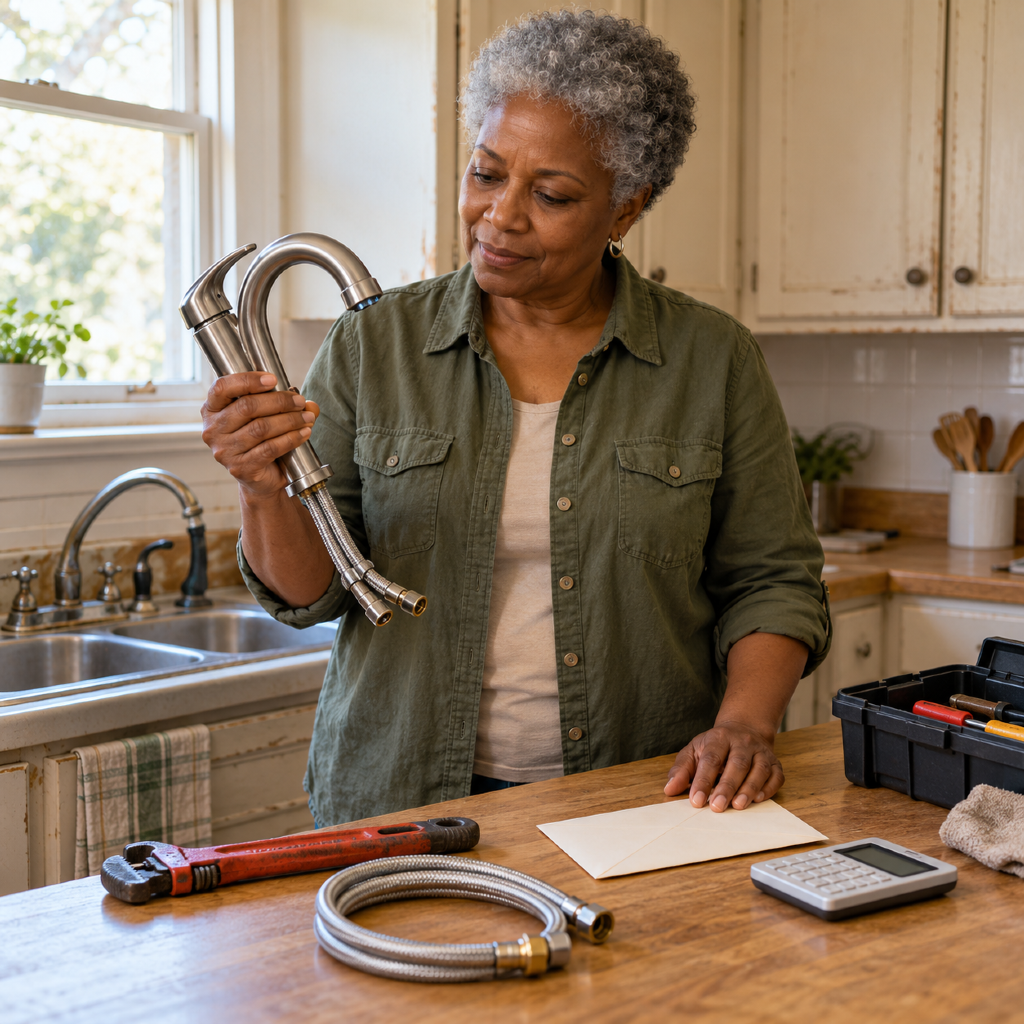
A home repairs sinking fund is a savings account or dedicated financial reserve you build specifically to cover home maintenance and repair expenses. Unlike general emergency or rainy-day funds, this money is set aside solely for roof replacements, plumbing issues, or heating and air conditioning repairs.
The purpose of this fund is simple: to create predictability out of unpredictable—or at least, hard-to-time—home costs. It’s a proactive measure, not just a responsive one. By deliberately planning and allocating money to this fund, you can smooth out the financial shock of large or frequent home repairs, especially as you age and rely more on fixed retirement income.
Typical uses during retirement
During retirement, homeowners often face more repair needs as their homes and their schedules age. Common uses of a home repairs sinking fund include replacing major appliances, fixing leaky roofs, addressing foundation issues, and keeping up with regular upkeep that prevents bigger problems. Setting aside funds in advance helps you avoid dipping into your monthly retirement income, investments, or emergency reserves when the unexpected happens.
Why Prepare for Unexpected Home Costs?
Risks of overlooking repairs
Neglecting or postponing essential home repairs can carry sizable risks. Small problems—like minor roof leaks or outdated electrical systems—can quickly worsen, leading to far more costly repairs. Worse, chronic neglect can significantly reduce your home’s value and usability. The longer these needs go unmet, the higher the potential for both financial outlay and disruptions to your living environment.
Retirement income and unplanned expenses
When living on a fixed or semi-fixed income, unplanned expenses like a burst water heater or a damaged roof can create major stress. You may be forced to sell investments in a down market or withdraw more than expected from retirement accounts, potentially affecting your long-term security. A dedicated fund for home repairs provides a buffer, helping you keep your carefully planned retirement income intact.
How Does a Sinking Fund Protect Retirement?
Income protection strategies
A home repairs sinking fund supports your income protection strategies by letting you plan for the unplannable. Instead of dipping into your monthly income or retirement savings to cover a surprise home expense, you draw from a resource designed specifically for that purpose. This separation keeps your day-to-day income planning steady, reduces anxiety, and limits the chance that you’ll need to disrupt your larger financial plan.
Reducing market risk exposure
A sinking fund also buffers against market risk. Without a fund, you might be forced to sell investments at unfavorable times or increase withdrawals in a market downturn, potentially locking in losses or jeopardizing long-term sustainability. By keeping funds in safe, liquid accounts, you reduce exposure to timing risks and market fluctuations, keeping your retirement trajectory on track.
Key Steps to Build a Sinking Fund
Calculating your potential repair needs
Start by evaluating your home’s age, condition, and unique repair schedule. Consider historical expenses for similar properties and consult maintenance schedules for items like roofs, HVAC, and major appliances. A reasonable starting point is to estimate annual repair costs—perhaps as a percentage of your home’s value—then adjust up or down based on your personal home’s needs. Periodically review and update this assessment as the property ages or after major repairs.
Integrating the fund into your plan
Once you have an annual goal, include the sinking fund in your broader retirement budget. Allocate regular, manageable contributions—monthly or quarterly—from your cash flow. The key is consistency. Treat this fund as non-negotiable, just like property taxes or insurance. If you receive lump sums (such as from downsizing or tax refunds), consider allocating a portion to give your fund an occasional boost.
What Are Safer Funding Strategies?
Principal protection approaches
For peace of mind, choose funding methods that focus on principal protection and liquidity. Favor federally insured accounts such as high-yield savings, money market accounts, or short-term CDs. These options generally protect principal, making them appropriate for funds you may need to access on short notice and with minimal value fluctuations.
Diversification for stability
If your fund’s size or your overall financial situation allows it, consider some limited diversification. You might maintain the core of your sinking fund in ultra-safe, liquid assets while splitting a small portion into slightly longer-term or stable-value vehicles for modest growth. The goal isn’t to chase returns, but to ensure stability and preservation so you’re well prepared for repairs when they arise.
How to Avoid Common Sinking Fund Mistakes
Overestimating or underestimating needs
It’s easy to misjudge either direction. Overestimating may tie up more cash than you need, potentially reducing funds available for other important goals. Underestimating means coming up short when a big repair arises. Review your estimates at least annually—and after any major home project—to keep your savings goals realistic and balanced for your actual property and location.
Balancing liquidity and stability
Another common pitfall is focusing too much on growth, which can erode the liquidity and principal protection a sinking fund requires. Remember, accessibility is crucial; funds shouldn’t be locked up in ways that make them hard or expensive to access when repairs come due. Seek a blend of stability and ready access to ensure you meet your fund’s purpose.