Key Takeaways
- Laddered maturity strategies in 2026 help balance risk and provide more predictable income streams.
- Understanding trends and suitability is essential for integrating laddering into your financial plan.
Looking ahead to 2026, many investors like you want practical solutions that balance risk with reliable income—especially as the landscape grows increasingly unpredictable. Laddered maturity strategies have emerged as a trusted approach, offering structure and peace of mind as you plan for retirement and protect your savings from market volatility.
What Is a Laddered Maturity Map?
Concept Overview
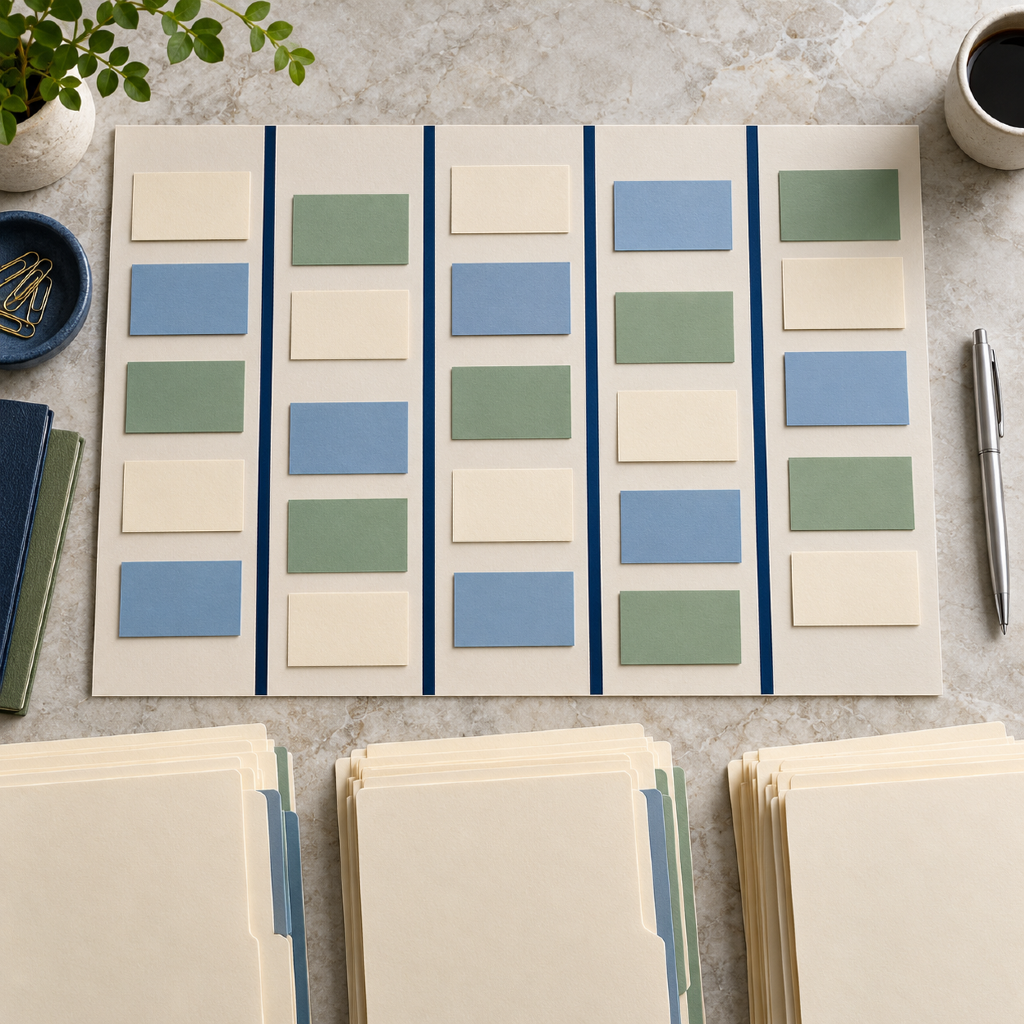
A laddered maturity map refers to a strategy where you spread investments—such as bonds, certificates of deposit (CDs), or other fixed-maturity financial vehicles—across different maturity dates. Instead of locking up all your funds in a single term, you “ladder” them to mature at staggered intervals. This helps avoid having all your capital exposed to the same interest rate or market cycle, supporting greater stability in both yield and access to funds.
Think of a laddered map as a timeline. Each rung represents an investment that matures at a specific time, letting you reallocate or access money strategically.
Common Applications
Laddered maturity maps are commonly used in retirement income planning, helping you align cash flow with future expenses—like healthcare or living costs. They also help manage liquidity needs and reduce market timing risk. Whether you’re nearing retirement or want steadier growth, laddering offers a straightforward way to plan ahead.
Why Consider Laddered Strategies in 2026?
Recent Market Shifts
Recent market conditions have highlighted the value of flexibility. Volatility, rising inflation, and economic shifts are prompting more people to seek solutions that don’t lock up funds for too long or expose everything to short-term market swings. In 2026, laddered maturity maps are increasingly relevant for anyone who wants balanced exposure while staying nimble in their financial decisions.
Interest Rate Environment
Interest rates have been dynamic, creating opportunities and challenges for savers. Laddering helps address uncertainty by positioning part of your savings to benefit from potential future rate increases. As rates change, periodic maturities give you chances to reinvest at current rates—without committing everything at a single point in time. This can smooth out the impact that rate changes have on your portfolio’s overall performance.
How Does Laddering Support Risk Management?
Reduced Exposure to Market Swings
By dividing investments across various maturities, laddering reduces your exposure to sharp market shifts on any single date. Instead of being fully vested in a market high (or low), you gain intervals to adjust and respond. This approach buffers against sudden drops in value or interest rate declines, supporting steady capital preservation over time.
Diversification Benefits
Laddering isn’t just about timing; it diversifies across time horizons. Diversifying maturity dates reduces the risk that a single adverse event affects all your investments. By staggering end dates, you help ensure that portions of your funds become available for reinvestment or spending consistently, even if part of the market underperforms.
Are Laddered Strategies Right for You?
Suitability Considerations
Laddered maturity maps aren’t a one-size-fits-all solution, but they align well with those seeking more secure, predictable cash flow. Ask yourself:
- Do you value liquidity and flexibility?
- Are you looking to reduce the impact of market swings?
- Is reliable income planning a key priority for your retirement?
Before considering laddered strategies, evaluate your risk tolerance, cash flow needs, and how important flexibility is to your financial plans. Remember, no investment strategy removes risk entirely, but laddering is designed to make risk more manageable.
Typical Investor Profiles
Many individuals approaching retirement, or retirees seeking stable income, value this approach. Conservative investors who prefer steady, lower-volatility growth over chasing higher, less predictable returns also use laddered maturity maps. If you’re prioritizing capital preservation and periodic access to funds, this approach could fit your overall goals.
Key Trends in Laddered Maturities for 2026
Short vs. Long-Term Laddering
In 2026, interest is growing in both shorter- and longer-term ladders. Shorter ladders (with maturities under five years) offer faster access to cash if your needs change or rates move unexpectedly. Longer ladders (10+ years) can lock in stability for future income certainty. Many investors blend both, balancing immediate needs with future goals.
Adapting to Economic Uncertainty
With the economy continuing to fluctuate, flexibility has become a key trend. Laddered strategies are evolving to allow more frequent adjustments, letting you realign as your priorities or the market shift. This adaptability is especially useful in uncertain times, supporting more resilient financial plans that can weather changes in policy, rates, and global conditions.
How Can Laddering Offer Income Stability?
Scheduled Income Streams
One of laddering’s biggest advantages is its ability to create regular, scheduled income. By having investments mature at different intervals—such as every year or every few years—you can plan for consistent cash inflows to match your spending needs. This structured approach helps you avoid the risk of having to withdraw all your funds at a potentially inopportune time.
Managing Reinvestment Risk
Reinvestment risk is the possibility that when an investment matures, you may have to reinvest at lower prevailing rates. Laddering helps manage this risk by spreading reinvestment points over time. If rates fall, not all your money is exposed to that change; if rates rise, upcoming maturities let you take advantage of higher returns. This can make your overall income stream steadier and less vulnerable to sudden drops from market changes.