Key Takeaways
- Preferred securities are sensitive to interest rate changes, which can affect income stability in retirement.
- Managing interest rate risk and maintaining portfolio balance are key for retirees considering preferreds.
Many retirees are surprised by how much rising interest rates can impact their steady-income investments. Understanding the connection between preferreds and interest rates is crucial for protecting your retirement savings as you plan for stability in 2026 and beyond.
What Are Preferred Securities?
Key features of preferreds
Preferred securities, often known as preferred stock, share qualities of both stocks and bonds. As an investor, you receive generally fixed dividend payments, similar to bond interest, but the security can also be traded like common stock. Preferreds are usually issued by financial institutions and large corporations seeking to raise capital.
One appealing aspect for retirees is that preferreds may provide steady income payments. They also typically rank higher than common stock in a company bankruptcy, but lower than bonds. This unique position offers a balance of income potential and relative stability.
How preferreds differ from common stock
You might wonder how preferreds are distinct from common stocks. Unlike common stockholders, preferred holders do not have voting rights in most cases. Preferred investors also have priority in dividend payments. However, unlike bonds, preferreds may not mature on a set date, and the issuing company might have the ability to call (redeem) the shares after a certain period.
Why Do Interest Rates Affect Preferreds?
Interest rate basics
To understand preferreds, it helps to know the basics of interest rates. When rates rise, newly issued securities offer higher yields, making existing income investments with fixed payments (like preferreds) less attractive in comparison. Conversely, when rates fall, those same fixed payments become more appealing, often increasing the value of existing preferreds.
Links between rates and preferred prices
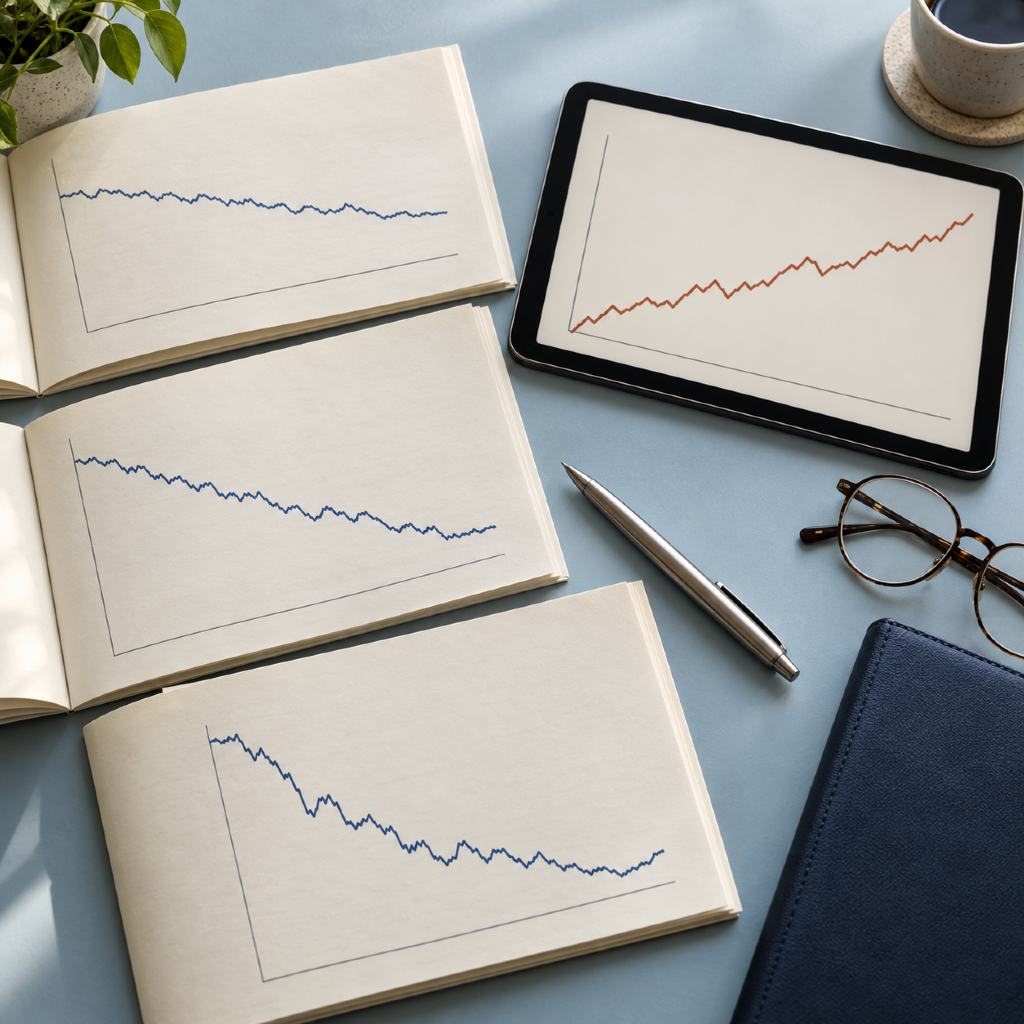
The connection between interest rates and preferred securities is clear: preferred prices generally move in the opposite direction from rates. If you hold preferreds and rates go up, your securities could lose value in the secondary market. Should rates go down, the prices of your preferreds might rise, but companies might also call them (redeem at par), sometimes limiting upside for investors seeking to benefit from lower rate environments.
How Sensitive Are Preferreds to Rate Changes?
Duration and price impact
Preferred securities tend to have what is known as “interest rate sensitivity” or duration – a measure of how much the price of a security is expected to change with a shift in interest rates. The longer the duration and the more fixed the payment stream, the more sensitive a preferred is likely to be to rate movements. For you as a retiree, this means the value of your preferred holdings could fluctuate as market rates change.
Real-world examples of rate shifts
Imagine rates increase significantly over a short period. The market value of existing preferreds, which pay lower coupons compared to new issues, may decline. If you purchased a preferred at $25 per share, but now new preferreds yield higher rates, your old shares could drop below par value if you try to sell. Conversely, if rates fall, your preferred could increase in value – but the issuer might call them back if the terms allow, capping your gain.
What Are the Main Risks for Retirees?
Income stability concerns
Many retirees invest in preferreds for predictable income. However, because preferred dividends aren’t guaranteed, issuers can defer or suspend payments during financial stress. Unlike bond interest payments, preferred dividends are generally at a company’s discretion, which can mean interruptions in your income stream during difficult periods for the issuer.
Inflation and purchasing power risk
Another major concern is inflation. If inflation outpaces the fixed income from your preferreds, your purchasing power can decline over time. Rising interest rates (often driven by inflation fears) can further reduce your portfolio’s market value, compounding the income-stability challenge.
Can Preferreds Help Diversify Retirement Income?
Role in overall asset mix
Preferreds can help diversify your retirement income. Because they are structured differently from bonds and stocks, adding them to your portfolio can potentially spread risk and add another income layer. The goal is to ensure your overall asset allocation is not overly concentrated in a single security type or sector, which could make your income stream vulnerable to market movements.
Comparing to other income sources
Compared to other income generators like bonds, annuities, or dividend-paying stocks, preferreds often sit in a unique niche. They may offer higher yields than some bonds, but with higher risk and greater price sensitivity to interest rates. Mixing several income types can help smooth volatility and sustain cash flow throughout retirement.
How Can Retirees Manage Interest Rate Risk?
Practical risk management strategies
Managing interest rate risk begins with understanding duration and how it impacts your preferreds. You can lower this risk by staggering maturities, mixing fixed- and floating-rate preferreds, or limiting the size of your preferred allocation. Monitoring issuers’ credit quality and paying attention to call features can also help strengthen the reliability of your income stream.
The importance of portfolio balance
Portfolio balance is essential. Relying too much on any single income source could expose you to greater swings if rates move unexpectedly. Review your allocation regularly, keeping a mix that matches your risk tolerance, time horizon, and income needs. This might mean blending preferreds with high-quality bonds, cash, or even inflation-protected instruments to help you weather different market conditions.
Are Preferreds Right for Every Retirement Plan?
Assessing individual risk tolerance
Preferred securities don’t suit every retiree’s goals or comfort with risk. You’ll want to consider your willingness to accept fluctuating prices and potential dividend interruptions. If losing principal, income volatility, or rate sensitivity would cause stress, you may need a conservative allocation or alternative strategies focused on preserving principal.
Questions to discuss with a financial professional
Before investing in preferreds, have an open conversation with a financial professional. Bring questions such as: How will preferreds fit into your whole retirement plan? What percentage of your portfolio is suitable? Are you comfortable with their risks compared to other sources? Tailoring your approach with trusted advice can help you avoid unwanted surprises down the road.