Key Takeaways
- Indexed universal life (IUL) can help protect your principal against market downturns while still offering growth opportunities.
- Strategic use of principal protection matters most in volatile markets, especially for those nearing retirement.
Navigating market risk is a growing concern as volatility rises in 2026. For many individuals, protecting your savings is a top priority—especially when looking ahead to retirement. In this article, you’ll explore how indexed universal life (IUL) can play a critical role in principal protection, and why this approach may matter more now than ever.
What Is Principal Protection?
Understanding principal preservation
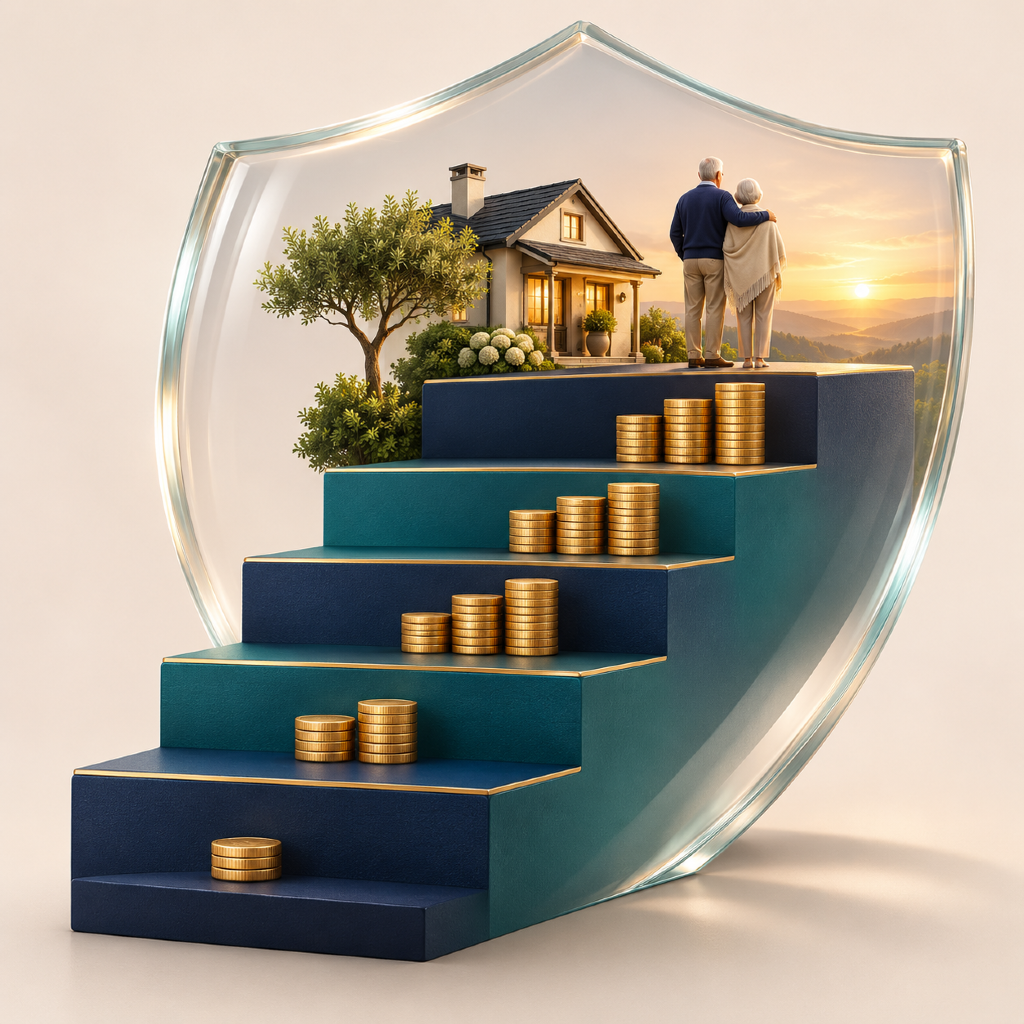
Principal protection refers to strategies that safeguard the original amount of money you invest—your principal—from market losses. By focusing on preserving your initial savings, you can reduce the risk of losing ground during unpredictable economic cycles. This concept remains central to many retirement and long-term planning strategies. It involves not only keeping the principal intact but also maintaining confidence that your portfolio can weather downturns.
Why principal protection matters
For those nearing retirement or seeking more stability, principal protection brings peace of mind. Large market corrections can delay retirement goals, impact income plans, or force difficult decisions about withdrawals. By preserving what you’ve already built, you provide yourself a more stable foundation to plan for evolving life and financial needs.
How Does IUL Offer Principal Security?
Fundamentals of indexed universal life
Indexed universal life (IUL) is a type of permanent life insurance policy that blends insurance protection with a cash accumulation feature. The cash value component can grow according to the performance of a chosen market index, often with certain guardrails in place. Unlike direct stock market investing, IUL typically limits downside risk—your cash value doesn’t decrease when the market index falls, but it can participate in some positive market performance during growth years.
Market risk vs. principal protection
Traditional market investments expose your funds to swings—sometimes big enough to wipe out years of growth. With IUL, the structure includes principal protection. The value credited to your policy generally never falls below zero due to index-linked losses. This safety net separates the IUL strategy from direct investments, offering stability for risk-averse savers who want to avoid seeing their balances shrink in a downturn.
What Makes Market Risk a Concern in 2026?
Current economic risk factors
As we move through 2026, economic signals point to ongoing volatility. Factors such as shifting interest rates, geopolitical uncertainties, and inflation pressures have made traditional investments less predictable. As these forces shape financial markets, investors are increasingly wary of sudden declines that can disrupt retirement planning or reduce net worth.
Recent trends impacting investors
Recent studies show more investors near retirement are shifting from growth-focused to protection-oriented strategies. Risk-adjustment interest has increased, with many households revisiting their allocations and seeking vehicles designed to weather downturns. Products like IUL have gained attention for their ability to shield principal while still presenting some upside potential in strong years.
Case Study: How Safe Strategies Helped
Scenario overview
Consider a couple in their late 50s, approaching retirement in just a few years. After experiencing a significant market correction earlier in the decade, they prioritized protection over higher risk. Their goal was to secure accumulated assets without missing out entirely on future growth opportunities.
Applying principal protection techniques
Working with an experienced financial professional, they included IUL in their risk management plan. This approach enabled them to:
- Insulate a portion of their savings from further market drops
- Retain some growth potential through positive index performance
- Build in flexibility to adapt as retirement approached
Throughout volatile market cycles, the principal amount they allocated to their IUL policy never went backward, even when other investments experienced temporary losses. This provided confidence during uncertain times and allowed them to plan ahead without fear of starting every recovery from a lower balance.
Who Can Benefit From IUL Strategies?
Individuals nearing retirement
If you’re within ten years of retiring, preserving what you have is often as important as seeking new growth. IUL can be a powerful tool for individuals who want to reduce exposure to major market losses while still pursuing moderate, index-linked accumulation. This stability can also make retirement income planning more predictable.
Households seeking stable planning
Families aiming for balanced financial health might look to IUL for its combination of insurance and steady cash value features. It can sit alongside other strategies—such as fixed-income or dividend-paying investments—to diversify risk and help provide reliable support for upcoming life changes, whether that’s a home purchase, college expenses, or healthcare costs.
Are There Limits to Principal Protection?
Understanding non-guaranteed factors
While IUL can help limit downside risk, it’s important to recognize that certain elements—such as index crediting methods, cap rates, and insurance costs—are subject to policy stipulations and broader market conditions. Cash value protection applies to market losses, but not necessarily to other factors, such as changes in contract terms or adjustments to cost components.
Regulatory and contract considerations
Principal protection through IUL ultimately depends on the policy’s contractual provisions and the regulatory environment. Insurance policies are subject to the issuing company’s claims-paying ability and local oversight. It’s essential to understand the details in your policy illustration, annual statements, and disclosures, and to weigh contractual guarantees alongside broader diversification goals.
Can Principal Protection Replace Other Strategies?
Diversification in risk management
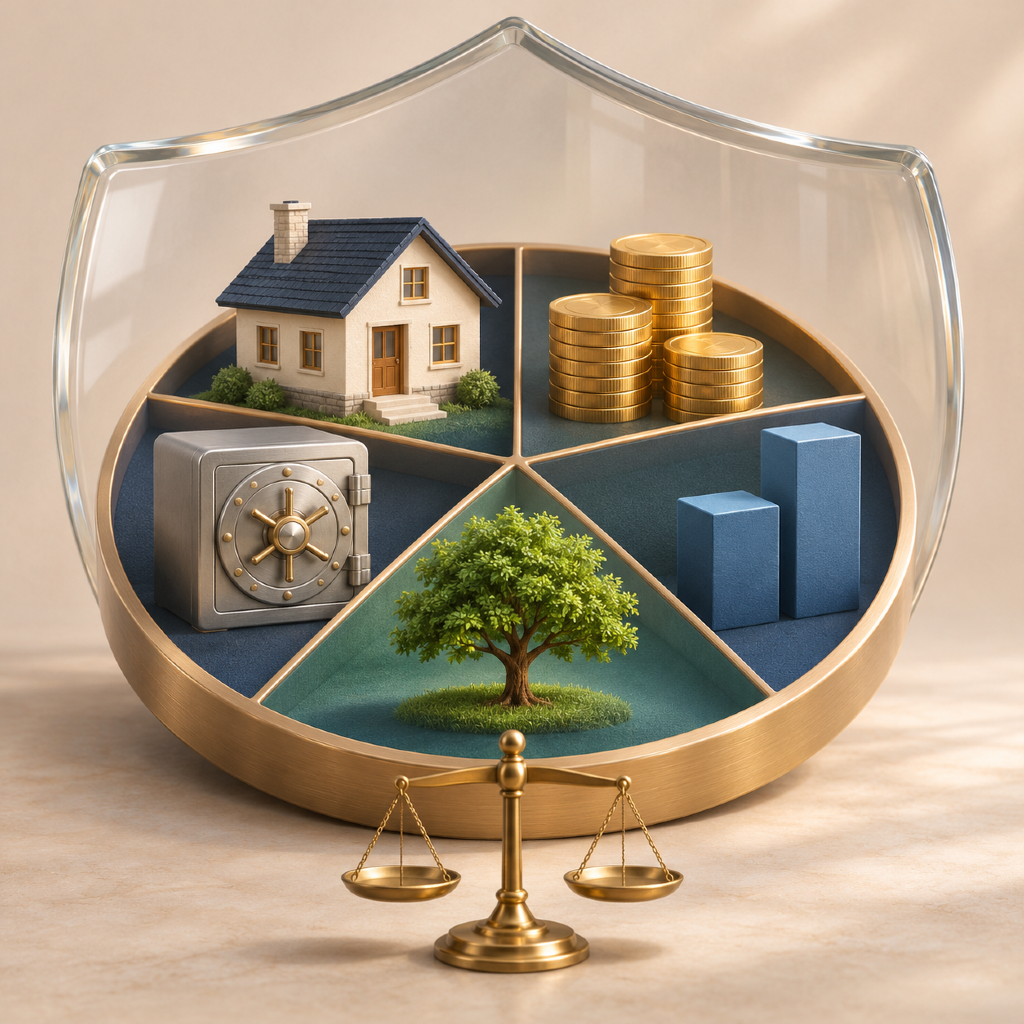
No single approach can fully address every financial need or risk. Even with an IUL in place, diversification remains a central principle in financial planning. By spreading savings across a variety of accounts, assets, or insurance vehicles, you reduce the risk of over-concentration and help insure against unexpected scenarios.
Blending protection with growth
Principal protection isn’t meant to replace growth strategies but to complement them. A thoughtful blend allows you to pursue gains in higher-risk assets while safeguarding the core of your portfolio. For many, this dual focus can provide peace of mind—knowing a portion of your nest egg is shielded no matter how market conditions evolve.