Key Takeaways
- Conservative investing focuses on stability, diversification, and risk awareness, not guaranteed outcomes.
- Evaluating your goals and risk comfort, with professional input, helps align strategies for safer retirement planning.
Are you concerned about preserving your savings as retirement approaches? Conservative investing emphasizes steady growth and limited risk, but structuring your portfolio and avoiding pitfalls takes clarity. Let’s break down the essentials with direct answers to common questions.
What Is a Conservative Portfolio?
Core Principles Explained
A conservative portfolio places stability and principal preservation at its core. This approach avoids high-volatility investments and instead prioritizes asset classes with steadier historical performance and lower exposure to market swings. The primary goal is to minimize the chance of substantial losses—especially critical as you get closer to retirement or rely on your savings for income.
Key principles include:
- Preservation first: Protect your initial investment (“principal”) from significant downturns.
- Predictability: Choose investments with more stable return patterns over aggressive growth.
- Income focus: Many conservative strategies emphasize generating steady interest or dividends, providing recurring income to help support retirement needs.
Types of Conservative Assets
Conservative portfolios often use asset allocations that rely on the following:
- Government and investment-grade bonds: These provide stability and a regular income stream, with historically lower default risk.
- Money market securities: Known for liquidity and low risk, money markets are commonly used for very short-term needs.
- High-quality dividend-paying stocks: While still part of the stock market, these stocks tend to offer lower volatility and ongoing income compared to riskier shares.
- Stable value products and insured accounts: Designed to reduce principal risk and smooth out market fluctuations.
It’s about finding the right balance—maximizing security while maintaining some growth potential.
Why Does Diversification Matter?
Spreading Risk Across Assets
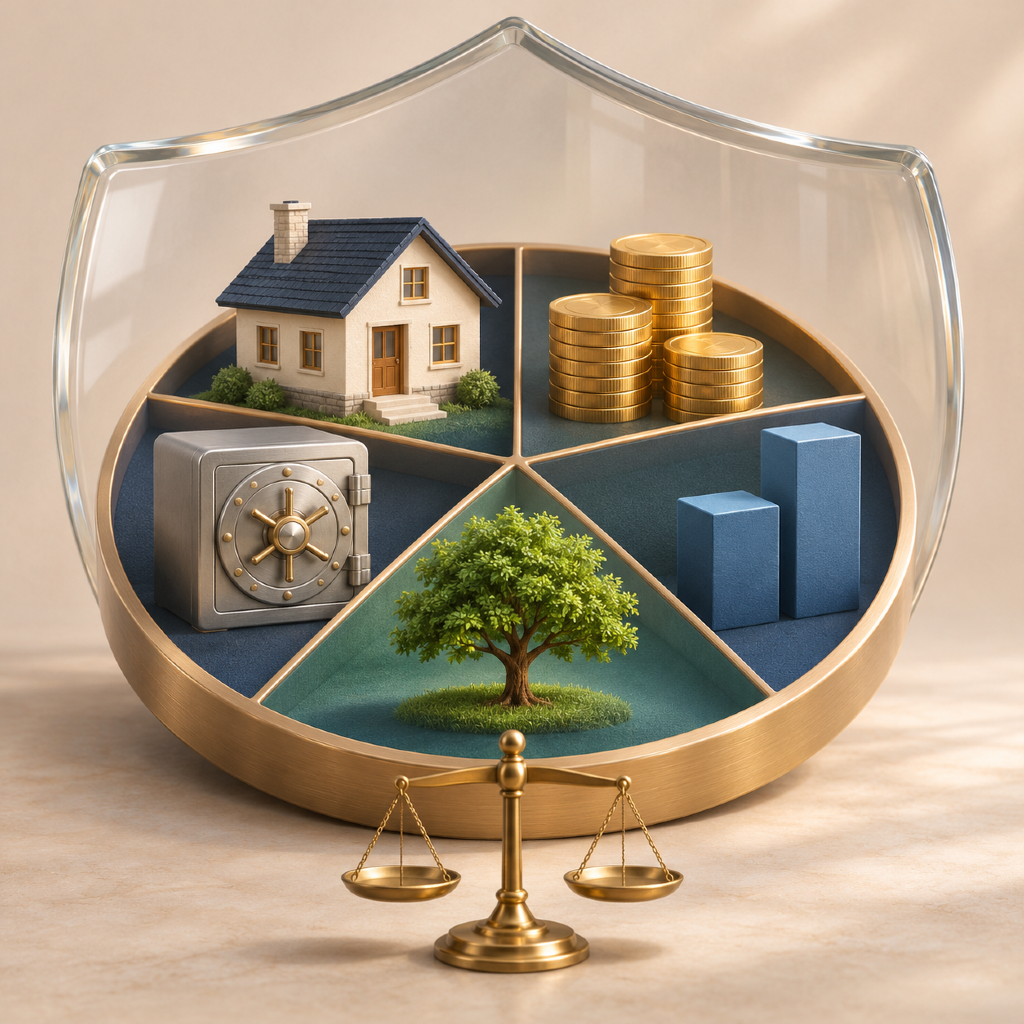
Diversification is a fundamental risk management technique. By spreading your investments among different asset classes, industries, and geographic regions, you help reduce the impact of any single asset’s downturn. For example, if one type of bond underperforms, other holdings like cash equivalents or stable stocks can help cushion the blow.
Diversification works because different investments react differently to economic conditions. The key is to avoid putting all your eggs in one basket—instead, craft a portfolio designed to withstand a range of market scenarios.
Long-Term Benefits for Retirees
For those entering or nearing retirement, diversification is more than a technical term—it’s a stability engine. A diversified approach helps guard against unexpected events (like sudden market downturns) that could erode your nest egg. By maintaining a blend of asset types, you aim for more predictable results and help ensure your savings support a lengthy and comfortable retirement.
How Can Risk Be Managed Effectively?
Understanding Risk Tolerance
Risk tolerance means how much fluctuation—positive or negative—you feel comfortable accepting in your investments. Everyone’s risk tolerance is unique: it depends on your age, years to retirement, existing savings, and even your emotional response to market changes.
Identifying your risk comfort level is a vital first step. Ask yourself:
- How would you react if your investments suddenly lost value?
- Are you willing to accept minor losses for modest growth?
- Would market declines cause you to panic and consider changing your plan?
Matching your strategy to your comfort level leads to better decisions over time.
Common Risk Management Strategies
Practical ways to manage investment risk include:
- Asset allocation: Adjust the mix of stocks, bonds, and cash to suit your needs and market outlook.
- Regular portfolio reviews: Rebalancing ensures your strategy remains on target as markets move over time.
- Discipline: Avoid impulsively reacting to market news—stick to your strategic plan.
- Use of conservative vehicles: Incorporate stable value or principal-protection strategies where appropriate, focusing on steady growth rather than chasing higher returns.
These steps aim to align your investments with both your goals and your comfort with risk.
What Questions Should Investors Ask?
Evaluating Personal Financial Goals
Before building or modifying a conservative portfolio, consider these questions:
- What are your most important financial objectives? (e.g., income, legacy, principal protection)
- How soon will you need to access these funds?
- Do you plan to take regular withdrawals, or are you building for the longer term?
- Are other income sources (like pensions or benefits) part of your picture?
These answers form the foundation of your overall strategy.
Balancing Safety and Growth
A completely risk-free approach rarely meets every need—growth is also necessary to outpace inflation and support long retirements. Think carefully about where you can accept moderate risk for thoughtful reward. Are you comfortable with a smaller allocation to stocks, or do you prefer to prioritize capital preservation above all?
Balancing stability with long-term growth is the art of conservative portfolio design.
Are Conservative Strategies Right for You?
Assessing Your Financial Situation
Deciding whether a conservative approach fits your needs depends on multiple factors:
- Your life stage: Are you approaching retirement, or already retired?
- Current savings: Does your portfolio already provide adequate security?
- Risk tolerance: How would you feel about market losses?
- Expected expenses: Do you anticipate stable or rising living costs?
Personalizing your investment strategy starts with understanding your unique financial situation.
Seeking Professional Guidance
Conservative investing involves many options, from asset classes to account types and risk management tools. Speaking with a qualified professional can help clarify the best educational approaches for you. Professionals can walk you through risk assessments, help with portfolio construction, and provide ongoing guidance—empowering you to make confident, well-informed decisions without product promotion.
What Are Common Misconceptions?
Debunking Risk Myths
Some believe conservative portfolios are completely safe or guarantee no loss. In reality, all investments carry some level of risk, including inflation risk (the chance your money loses purchasing power over time). Even highly stable assets can produce lower returns, so being conservative means managing—not eliminating—risk.
Understanding Limitations
It’s also important to recognize what conservative portfolios can and cannot do. While they focus on stability and protection, they may not provide rapid gains. If your goals require higher growth, you may need additional steps. Ultimately, aligning expectations with reality helps prevent disappointment—and encourages wiser planning.
FAQ: More on Safe-Money Planning
Protecting Principal in Volatile Markets
In turbulent markets, strategies such as regular portfolio reviews, disciplined rebalancing, and keeping a sufficient cash cushion can help shield your principal. Diversification and a focus on high-quality, lower-volatility investments are also key defenses.
Income Planning Considerations
Income from conservative portfolios often comes from interest, dividends, or systematic withdrawals. Review your income plan regularly to ensure it supports your lifestyle needs and accounts for inflation. Consider staggered withdrawal strategies that balance income stability with long-term growth.