Key Takeaways
- An emergency fund offers crucial security, helping retirees manage unexpected expenses without disrupting long-term plans.
- Balancing emergency savings with growth opportunities keeps you flexible and protected for retirement.
Building a robust financial foundation is essential for a confident retirement. An emergency fund stands at the core of this security, providing a buffer against unexpected expenses, especially when your income is more predictable or fixed. Let’s explore why and how you can make this core safe-money strategy work for you.
What Is an Emergency Fund?
Basic definition and purpose
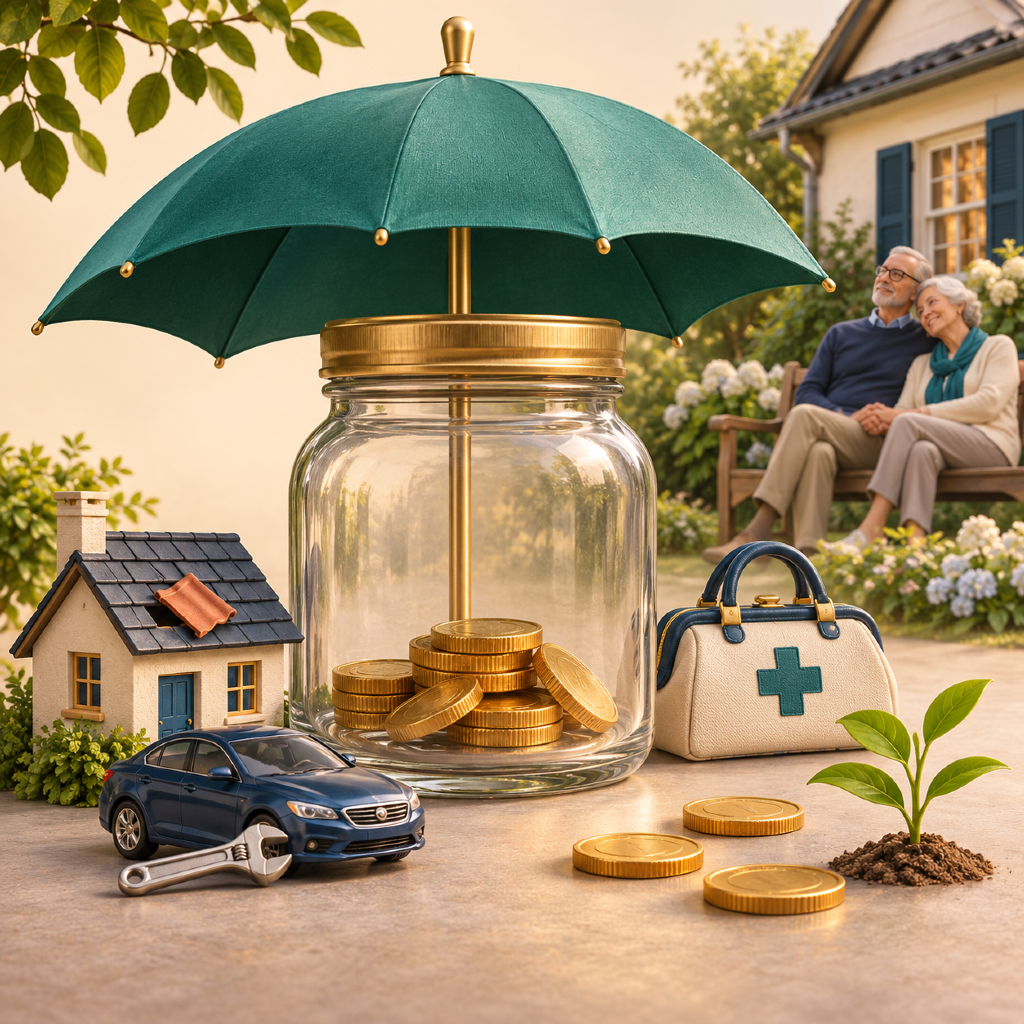
An emergency fund is a reserve of easily accessible money set aside to meet unplanned expenses. The primary purpose is to help you cover unexpected costs—such as medical emergencies, car repairs, or home maintenance—without interrupting your regular cash flow or dipping into long-term investments. It acts as a financial safety net, offering quick liquidity during critical moments.
How it relates to retirement planning
When you enter retirement, your income often becomes less flexible, relying more on predictable sources like Social Security, pensions, or income built from years of saving and investing. Unexpected withdrawals from retirement accounts can disrupt your long-term plans. An emergency fund keeps you from tapping into those essential savings or selling investments at the wrong time, protecting your retirement trajectory.
Why Do Retirees Need Emergency Funds?
Common unforeseen retirement expenses
Life can be unpredictable—retirement is no exception. Retirees may face unexpected dental work, out-of-pocket healthcare costs, home repairs after weather events, or even the need to support family members. Sometimes, expenses arise faster than income sources can adapt, making a dedicated emergency fund especially useful.
Impact on long-term financial security
Without an emergency reserve, you might be forced to withdraw from retirement accounts during market downturns or incur taxes and penalties for early withdrawals. These unplanned actions can jeopardize your financial stability and the longevity of your retirement income.
How Does an Emergency Fund Support Retirement?
Reducing risk from unexpected events
An emergency fund reduces the risk that a sudden expense will throw off your retirement plan. Instead of interrupting your carefully constructed income and withdrawal schedule, you can address financial shocks directly—without reacting hastily or compromising your broader goals.
Protecting other retirement assets
Access to ready cash means you don’t have to liquidate investments during market lows or lock in losses unnecessarily. It preserves your principal and allows your other savings to work toward your long-term objectives, rather than being depleted by immediate needs.
What Are the Pros of Having One?
Financial peace of mind
Knowing you have a cash reserve provides reassurance that you’re prepared for life’s financial surprises. This peace of mind can relieve stress, support your decision-making, and help you avoid impulsive actions that might harm your retirement strategy.
Flexibility during market fluctuations
If financial markets decline or income sources shift, your emergency fund provides a buffer, letting you wait out turbulence without permanently changing your investment or withdrawal plans. This flexibility can be especially valuable during periods of economic stress.
Are There Any Cons to Consider?
Potential opportunity costs
Money set aside in an emergency fund often sits in lower-yield, highly liquid accounts. While this ensures quick access, you may miss out on potential returns if you invested those funds for growth.
Liquidity versus long-term growth
There’s an inherent trade-off: prioritizing liquidity may mean your funds don’t keep up with inflation or grow over time. Balancing the need for immediate access with the desire for your money to work for you is an ongoing challenge in retirement.
How Much Should You Set Aside?
Factors influencing emergency fund size
There’s no single answer—your ideal fund size depends on monthly expenses, health status, insurance coverage, housing situation, and your comfort level with financial uncertainty. Retirees typically consider six to twelve months of living expenses as a starting point, but your personal situation may warrant more or less.
Strategies to gradually build savings
If you’re still working, consistently setting aside a small portion of each paycheck is a proven approach. Already retired? Consider diverting a fraction of discretionary spending or reallocating small windfalls. The goal is to build this reserve without straining your current lifestyle or overall plan.
What Are Alternatives to Cash Emergency Funds?
Exploring other safe-money strategies
While a traditional cash emergency fund is the standard, other approaches may include laddered certificates of deposit, short-term fixed income strategies, or certain money market instruments. Each option aims to balance stability with a degree of return while preserving liquidity.
Comparing diversification options
Diversification remains a core principle for retirement security. Blending cash, short-term secure assets, and highly liquid investments can help you fine-tune your approach—meeting immediate needs while supporting overall growth.
Is an Emergency Fund Always Necessary?
Situational factors for retirees
Not every retiree faces the same risks. If you have significant guaranteed income sources or minimal recurring expenses, you may need a smaller emergency fund. Conversely, those with unpredictable costs or heavy reliance on market-based income may benefit from a more substantial reserve.
Balancing emergency savings with other needs
The right balance depends on your unique situation. Consider how much you need available at all times versus how much you’d like to put toward long-term growth. A flexible, adaptive approach—reviewed regularly—keeps your finances resilient as your life and needs evolve.