Key Takeaways
- A CD ladder can help you protect your principal while maintaining liquidity and managing interest rate risk.
- Recent market trends in 2026 highlight the importance of stable, safe money strategies for retirement planning.
If you’re seeking a way to shield your savings from uncertainty in 2026, a CD ladder offers a structured, reliable option. In this article, you’ll learn how CD ladders work, their principal protection benefits, current trends, and actionable steps for setting one up to secure your future.
What Is a CD Ladder Strategy?
Core concept explained
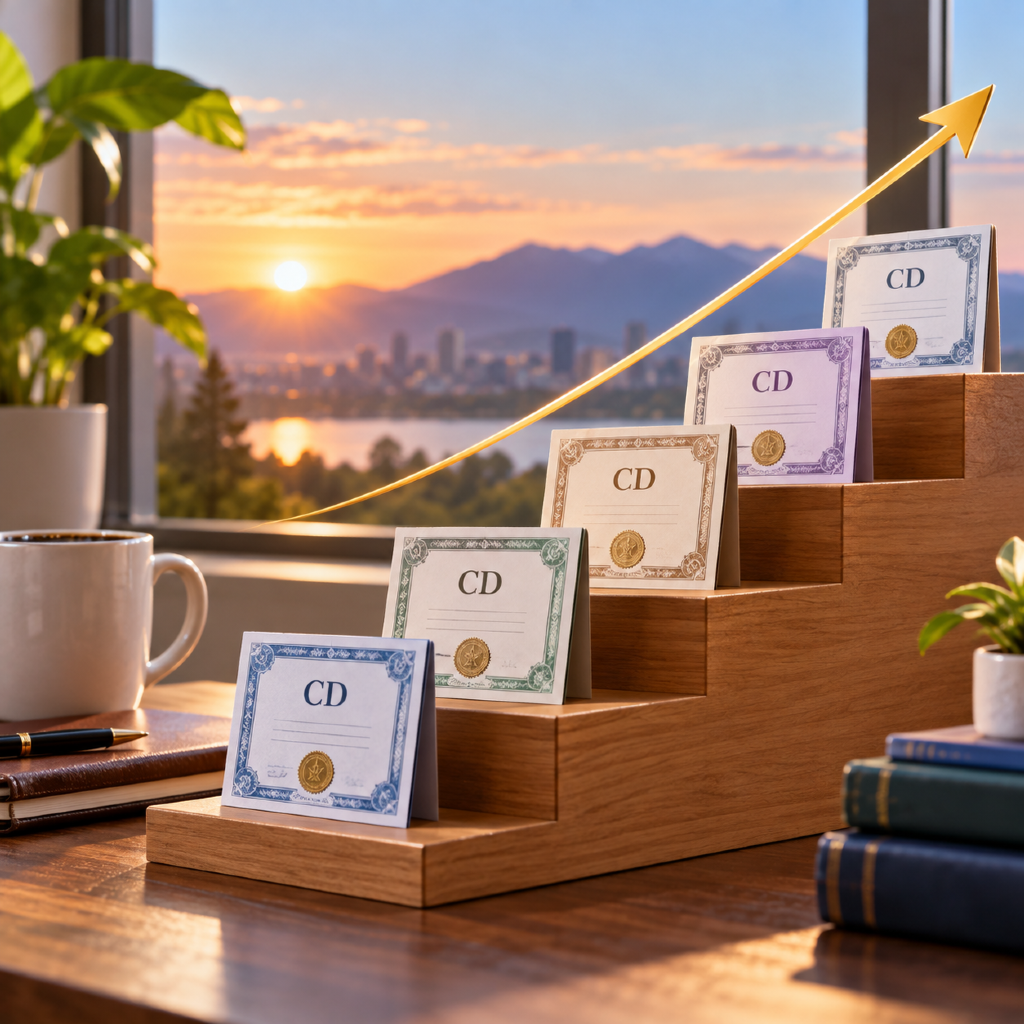
A CD ladder is a financial strategy that involves dividing your investment across multiple certificates of deposit (CDs) with staggered maturity dates. CDs are time deposits offered by financial institutions and are known for their defined term lengths and predictable returns. By arranging your CDs to mature at regular intervals, you create a ladder-like structure that maintains both security and flexibility.
How laddering works in practice
Imagine splitting your deposit evenly across several CDs set to mature at different times (for example, one, two, three, and four years). As each CD matures, you can reinvest in a new term or access the proceeds, creating ongoing flexibility. This staggered approach allows you to benefit from periodic liquidity and potentially capitalize on changing interest rate environments. You’re not locked into one long-term account—instead, you maintain access to portions of your investment every year.
How Does a CD Ladder Protect Principal?
Principal protection mechanisms
One of the central advantages of a CD ladder is the built-in principal protection. Because CDs are typically issued by regulated financial institutions and often insured up to applicable limits (such as by the Federal Deposit Insurance Corporation or similar entities), your original investment is safeguarded against loss, as long as you adhere to the deposit rules. The structure of a ladder means only a portion of your funds are exposed to each term period, reducing concentration risk.
Risks addressed by laddering
While all investments carry some level of risk, a CD ladder manages several key concerns. Interest rate changes can create uncertainty, but a ladder reduces the risk of locking your entire sum into a rate that quickly becomes outdated. By spreading maturity dates, you can reinvest maturing CDs at new, potentially more favorable rates. Furthermore, because CDs are generally not exposed to market volatility, your principal remains protected from the kinds of losses that can be seen in stocks or mutual funds.
Why Is Principal Protection Important in 2026?
Current market trends impact
Financial markets in 2026 continue to display both opportunity and vulnerability. Recent economic events—ranging from shifts in central bank policies to unpredictable inflation patterns—have pushed many individuals closer to retirement to prioritize security over aggressive growth. The demand for safe money solutions is at record highs, as more people seek consistent, insured preservation of their core capital.
Risk factors influencing decisions
Uncertainty about interest rates, global events, and increased volatility have all contributed to heightened concern for principal protection. Protecting your core savings is essential to ensure that short-term fluctuations do not derail long-term goals like retirement income. CD ladders give you a sense of stability, so unexpected downturns or changing economic conditions have limited impact on your principal.
What Are the Steps to Set Up a CD Ladder?
Step 1: Assess financial goals
Before you begin, clarify what you want your CD ladder to accomplish. Are you looking to access funds annually, or would you prefer to lock them away for longer spans? Pinpointing your liquidity needs and retirement timeline will help you structure your ladder effectively.
Step 2: Select term lengths
Decide on the number of rungs (CDs) in your ladder, and choose different maturities—often ranging from one to five years. The more rungs, the more options you’ll have for reinvestment or withdrawal as CDs mature. Common ladders use intervals such as one, two, three, and four years to balance flexibility and yield.
Step 3: Allocate investment
Divide your funds equally among the CDs according to your ladder design. Allocating your investment this way means you’ll have a portion of your initial deposit maturing at each scheduled interval, smoothing out interest rate risks and providing an ongoing source of cash flow or reinvestment opportunities.
Step 4: Schedule renewals
As each CD matures, decide whether to use the funds or roll them into a new CD at the ladder’s longest term. Maintaining the ladder’s structure is crucial to keep your schedule of maturity and liquidity steady. This cyclical process can be automated or managed manually, based on your preference.
How Have CD Ladder Strategies Changed Recently?
Recent developments in CD laddering
Over the past few years, interest in CD laddering has surged, particularly as more investors search for reliable, low-volatility strategies. Enhanced digital platforms now allow you to track, automate, and adjust your ladders more conveniently than ever. Flexible products and broader choices in term lengths have made it easier to tailor a ladder to your unique timeline and needs.
Impact of economic shifts
Economic shifts in recent years, such as central bank policy adjustments and inflationary pressure, have prompted many to explore principal-protected income approaches. For some, the opportunity to access maturing funds regularly is more appealing than committing to longer, high-yield investments with greater uncertainty. Ladders have grown in popularity as individuals look for balance between predictable returns and occasional access to cash.
Are There Alternatives for Principal Protection?
Other safe money approaches
While CD ladders are a reliable method for principal protection, you may consider other safe money avenues. Savings accounts, money market accounts, and certain fixed annuities can also help shield your capital. Each strategy comes with its own balance of risk, liquidity, and potential yield. The right fit depends on your specific needs and comfort with access, rate conditions, and time horizon.
Diversification considerations
No single approach can eliminate risk entirely, which is why diversification is a foundational element of safe money planning. By combining a CD ladder with other protected options, you can further insulate your savings against unexpected developments. Diversification helps reduce the impact of shifts in any one area, improving long-term resilience and stability in your portfolio.