Key Takeaways
- Bond ladders provide a structured way to reduce interest rate risk and support principal protection for retirement income stability.
- Implementing a bond ladder involves diversification, greater flexibility, and planning aligned with your financial goals and risk tolerance.
Are you looking for financial strategies that help safeguard your savings while offering reliable income during retirement? A bond ladder could be your answer. In this guide, you’ll find a clear overview of bond ladders and how they can help manage risk, protect principal, and support long-term financial stability.
What Is a Bond Ladder?
Basic structure and definition
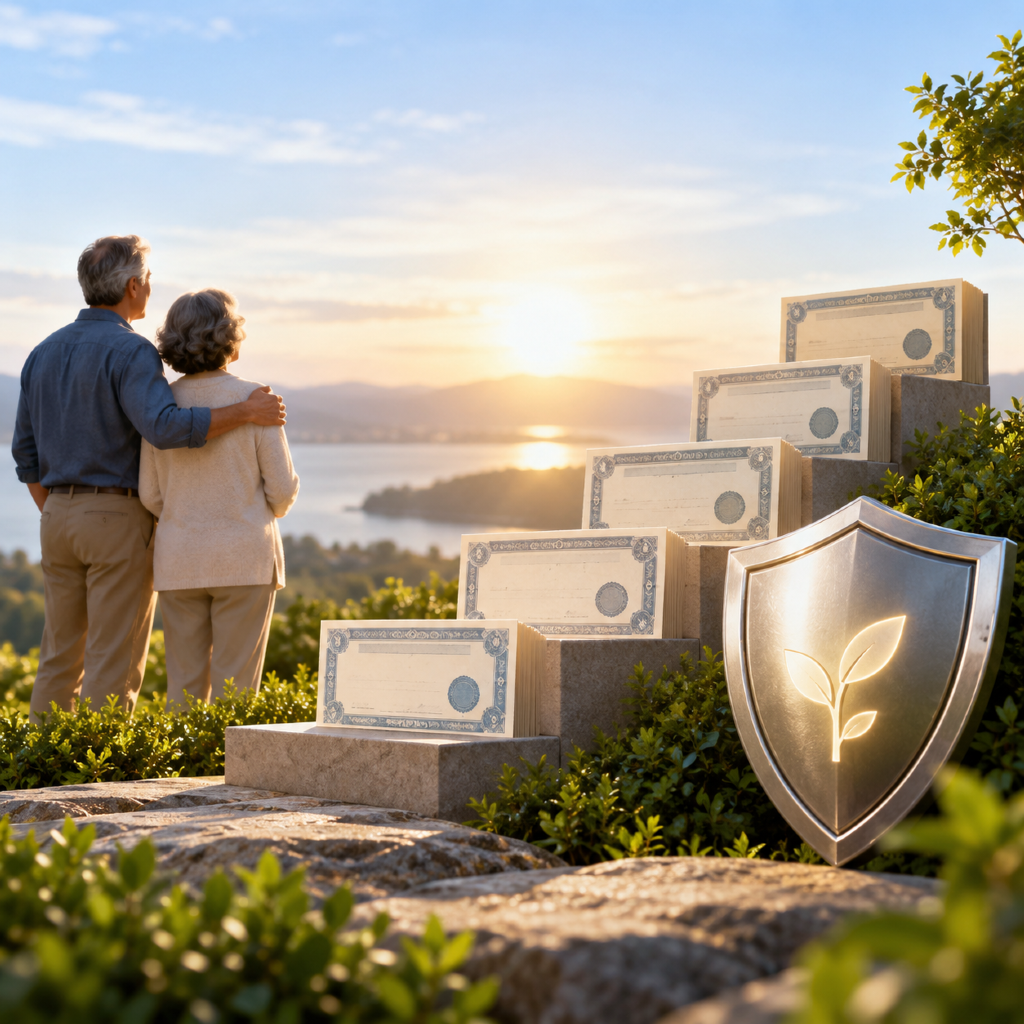
A bond ladder is an investment strategy that involves purchasing multiple bonds with staggered maturity dates. Instead of putting all your money into a few long- or short-term bonds, you spread your investment across many bonds that mature at regular intervals, such as every year or every few years. This creates the visual effect of “rungs” on a ladder when you line up the bonds by maturity date.
How bond ladders work over time
Each time a bond “matures” on your ladder, you get your principal back, which you can then use for spending or reinvestment. As older bonds mature, you have the flexibility to buy new bonds, adapt to changing interest rates, or access funds if needed. This rolling structure allows you to maintain both liquidity and a steady income stream, since the ladder continually replenishes itself over time.
How Does Principal Protection Work?
Understanding principal protection
Principal protection refers to strategies or products designed to help preserve the original amount of money you invest. In a bond ladder, principal protection is supported by choosing high-quality bonds and holding them to maturity. By investing this way, you avoid locking money in at a single interest rate or being fully exposed to market upticks and downturns. If held to maturity, the issuer pays back your original investment, assuming no default occurs.
Factors influencing safety and risk
The level of principal protection in a bond ladder depends on several factors. The credit quality of the bonds (for example, government or high-rated corporate bonds) plays a significant role in the safety of your original investment. Spreading investments across different issuers and maturities further reduces the chance that a single bond’s underperformance will impact your entire ladder. Always remember, while bond ladders are typically lower-risk compared to some investments, they do not eliminate risk altogether—the issuer’s ability to pay, market conditions, and inflation are all influential factors.
Can Bond Ladders Reduce Risk?
Diversification across maturities
One of the most effective features of a bond ladder is diversification. By investing in bonds with a range of maturity dates, you reduce the impact of interest rate swings and avoid concentrating risk in a single investment period. This approach smooths out fluctuations, since not all bonds will be affected equally by changing market conditions. Diversification also provides access to periodic liquidity as bonds mature in sequence.
Interest rate risk and laddering
Interest rate risk happens when changes in market rates affect the value of your existing bonds. With a ladder, you are not tied to just one rate environment; as each bond matures, you can potentially reinvest at current, possibly higher, interest rates. This staggered approach makes you less likely to lock in unfavorable returns, making your portfolio more adaptable to market shifts over time.
Why Consider Safe Money Strategies?
Preserving retirement income options
For those nearing or in retirement, the need for steady and predictable income becomes paramount. Safe money strategies, like bond ladders, are designed to help preserve both your capital and your access to income. Since bonds within a ladder mature at regular intervals, you can plan for known cash flows, supporting expenses like healthcare, travel, or simply maintaining your lifestyle throughout retirement.
Managing risk tolerance
Understanding your personal attitude toward risk is essential in retirement planning. Bond ladders empower you to take a balanced approach—reducing reliance on any single maturity date or market condition. By building a ladder that matches your comfort with market exposure and liquidity needs, you can avoid unnecessary anxiety during market fluctuations.
Key Benefits of Building a Ladder
Flexible access to funds
One of the strongest advantages of a bond ladder is flexibility. You regularly gain access to portions of your principal as each rung matures, without needing to sell bonds prematurely (which can lock in losses or forfeit potential interest). This timely access is especially useful if your circumstances or spending needs change.
Reduction of reinvestment uncertainty
Reinvestment risk—the risk that maturing bonds will need to be reinvested at lower rates—can disrupt retirement income planning. A laddered approach helps mitigate this risk since maturing bonds are continually spread out over varying rate environments. Rather than facing all-or-nothing reinvestment at a single time, you adapt gradually to evolving rates, smoothing out potential income fluctuations.
How to Start a Bond Ladder
Setting retirement income goals
Begin by defining what you want your ladder to achieve. Are you focused on generating a steady income, preserving capital, or both? Consider your anticipated expenses, the length of your retirement, and any non-negotiable financial commitments. Clear goals ensure your ladder’s structure aligns with your financial plan.
Choosing bond types and maturities
There are several types of bonds—government, municipal, and high-quality corporate bonds are some commonly used options. Choose bonds with differing maturity dates that align with your withdrawal schedule. For example, you might set up maturities every year for the next five or ten years, creating a predictable stream of principal returns for reinvestment or spending, depending on your needs.
Common mistakes to avoid
A few pitfalls can undermine the effectiveness of your ladder. Avoid over-concentration in a single issuer or maturity year. Don’t neglect the credit quality—higher yield often means higher risk. Also, avoid building a ladder that’s too short or too long without considering your liquidity needs and market outlook. Review your ladder regularly with a financial professional to keep it aligned with your goals and risk tolerance.