Key Takeaways
- Safe harbor allocation models balance principal preservation and income stability for retirement planning.
- Regularly review and understand your personal risk tolerance to protect retirement income effectively.
Not many Americans feel confident they’ll have enough for retirement—a gap that safe harbor allocation models aim to address with clearer strategies for stability and principal protection. As retirement nears, the need for steady income and protection against market downturns becomes more important than ever. Here’s what you need to know about these strategic allocation methods and how they might support your financial confidence.
What Are Safe Harbor Allocation Models?
Origins and evolution
Safe harbor allocation models emerged to address the uncertainties associated with retirement planning, especially during periods of market turbulence. Academic insights and regulatory frameworks shaped their evolution by providing greater protection for individual investors. As people recognized the vulnerability of their savings to market swings, financial professionals and researchers sought systematic ways to minimize unnecessary risk and reduce retirement income shocks.
Core principles explained
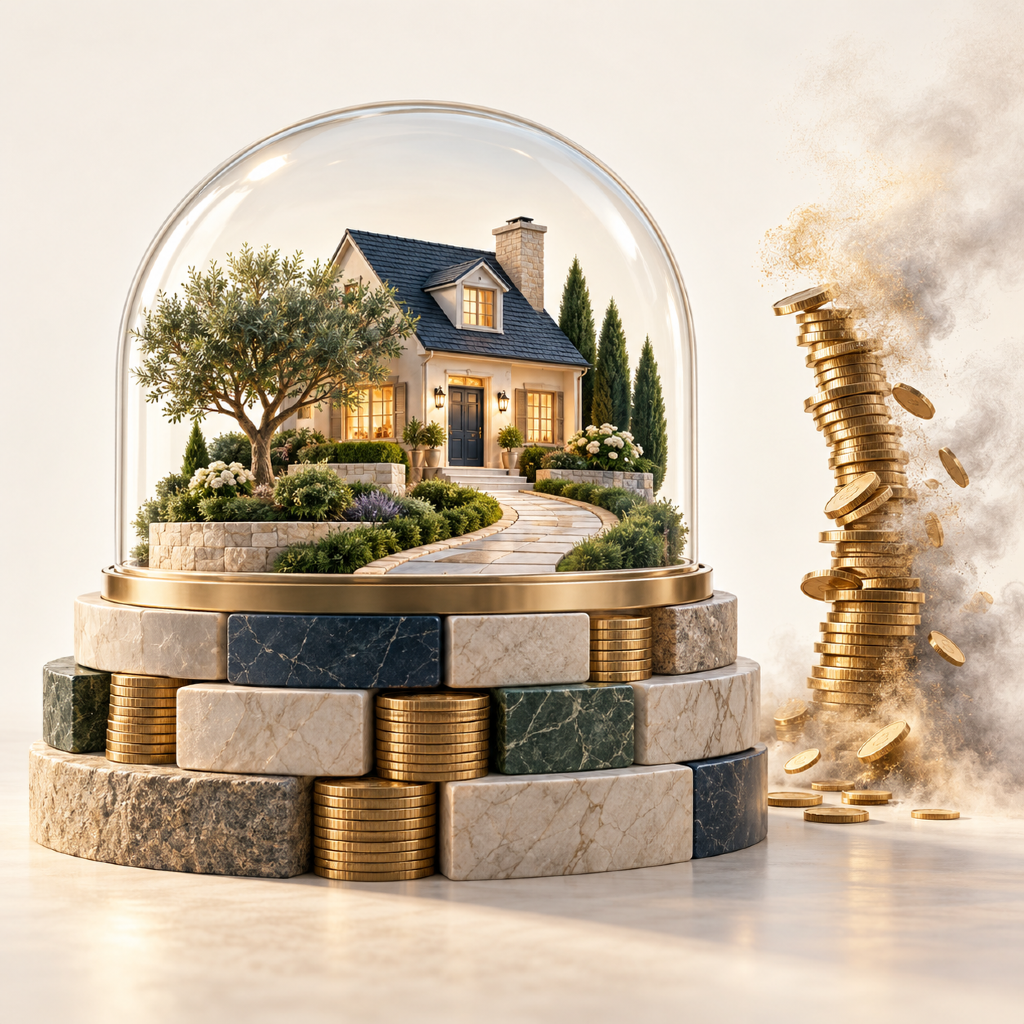
At their core, safe harbor allocation models aim to preserve capital while still generating income. They do this by combining asset classes and risk controls to protect your principal, even when markets become volatile. These models are typically rules-based and favor diversification, risk management, and periodic portfolio adjustments. They focus less on speculative growth and more on protecting what you’ve saved so it can reliably support your financial needs over the years.
Why Do They Matter for Retirement?
Preserving principal in volatile markets
Market downturns can hit your retirement portfolio harder—especially once you begin drawing income. Safe harbor models are structured to cushion you from such downturns, prioritizing principal preservation. By allocating a portion of your assets to more stable investments and using risk-management techniques, these models limit the impact of sharp market drops.
Supporting income stability
Predictable and steady income plays a crucial role in retirement well-being. Safe harbor allocation models aim to smooth income by allocating resources to lower-volatility assets and using disciplined rebalancing. This stability can help you cover essential expenses and reduce the emotional stress of large market swings, providing peace of mind as you transition from accumulation to distribution.
Key Best Practices for Implementation
Balancing risk and protection
Implementing a safe harbor strategy requires balancing risk reduction with sufficient growth to meet your retirement needs. As you approach or enter retirement, consider allocating larger portions to capital-preserving assets while still retaining some growth-oriented elements to offset inflation. Diversification across asset classes is a key tool—spreading risk to reduce the chance that a single market event could undermine your retirement security.
Reviewing and adjusting allocations
A safe harbor model is not a “set it and forget it” approach. Regularly reviewing your allocations keeps your strategy aligned with current market conditions, life changes, and evolving retirement goals. Experts recommend setting a schedule to review your portfolio, accounting for major life milestones or economic shifts. Adjustments should be methodical and focused on sustaining protection and reasonable long-term growth potential.
What Should You Consider Before Choosing?
Assessing personal risk tolerance
Choosing a safe harbor model should begin with an honest assessment of your own risk tolerance. How comfortable are you with potential fluctuations in your account balance? Your response can help determine how much of your portfolio to allocate to capital-preservation options versus growth-oriented assets. Reflect on prior market downturns and your reaction—this can guide how conservatively or flexibly you may want your allocations set up.
Understanding time horizons
Time horizon is another important factor. If you’re close to retirement, or already drawing income, protection often takes precedence over aggressive growth. In contrast, if you have several years before you’ll need to access funds, you can take a more measured approach to balancing risk and return. Align your allocation decisions with when you’ll need funds and how long you expect them to last.
Common Retirement Allocation Questions Answered
How often should you review your allocations?
Regular portfolio reviews are essential to ensure your allocations remain aligned with your financial objectives. For most people, reviewing at least once a year, or after a major life event, is a reasonable standard. Prompt reviews after major market shifts also help keep your retirement plan on track.
Can safe harbor models adapt to market trends?
Yes, most safe harbor allocation strategies are designed to adapt periodically to changes in market conditions. By relying on predefined rebalancing and risk-reduction rules, these models help you avoid impulsive decisions that could undermine your long-term stability. However, you should always weigh flexibility against the need for protection and a consistent income plan.
Exploring Limitations and Risks
Potential trade-offs to consider
While safe harbor allocation models provide meaningful protection, they still involve potential trade-offs. Prioritizing principal preservation can mean lower expected returns than more aggressive growth strategies. Excessive conservatism may also expose your assets to inflation risk, gradually eroding purchasing power over time. Recognizing these trade-offs is crucial before committing to a specific allocation strategy.
When might other strategies fit better?
Alternative retirement strategies may be more suitable in some cases. For instance, if your financial situation allows greater risk tolerance, you may consider a more growth-focused approach earlier in retirement planning. Individuals with unique financial objectives or more complex estates may also need a blend of strategies, combining safe harbor with other allocation models tailored to their needs.
How to Start with Safe Harbor Models?
Seeking educational resources
Effective retirement income protection starts with education. Reputable online resources, workshops, and seminars can give you a foundational understanding of safe harbor allocation options. Many financial education platforms offer unbiased guides and tools to support your decisions.
Consulting with financial professionals
Although self-education matters, consulting an experienced financial professional adds clarity and reassurance. Advisors can help you objectively assess your needs, risk profile, and retirement goals, and help you build a compliant safe harbor allocation tailored to your situation. Before finalizing any collaboration, ask about fees, fiduciary standards, and their familiarity with income-protection models.
In summary, safe harbor allocation models offer an education-driven path to balancing security and sustainable retirement income. Regular review, clear understanding of your goals, and a commitment to ongoing learning all strengthen your ability to protect your nest egg in a changing financial world.