Key Takeaways
- Life insurance can supplement retirement income during market downturns, reducing the impact of volatility.
- Evaluating safe-money strategies may lead to greater confidence and stability in your retirement plans.
Market ups and downs pose real challenges for those living on retirement savings. If you’re concerned about maintaining stable income throughout retirement, it’s important to learn how certain strategies—like using life insurance as a volatility buffer—can help protect your hard-earned savings and peace of mind.
What Is a Volatility Buffer?
Defining volatility in retirement
Retirement brings unique financial risks. One key risk is market volatility: unpredictable swings in the value of your investments. While these ups and downs are normal, their impact during retirement can be much more severe. Why? Because you’re withdrawing income from your savings, not just letting your money grow. If you’re forced to sell assets during a downturn, you lock in losses, which can jeopardize your long-term income.
Introducing the volatility buffer concept
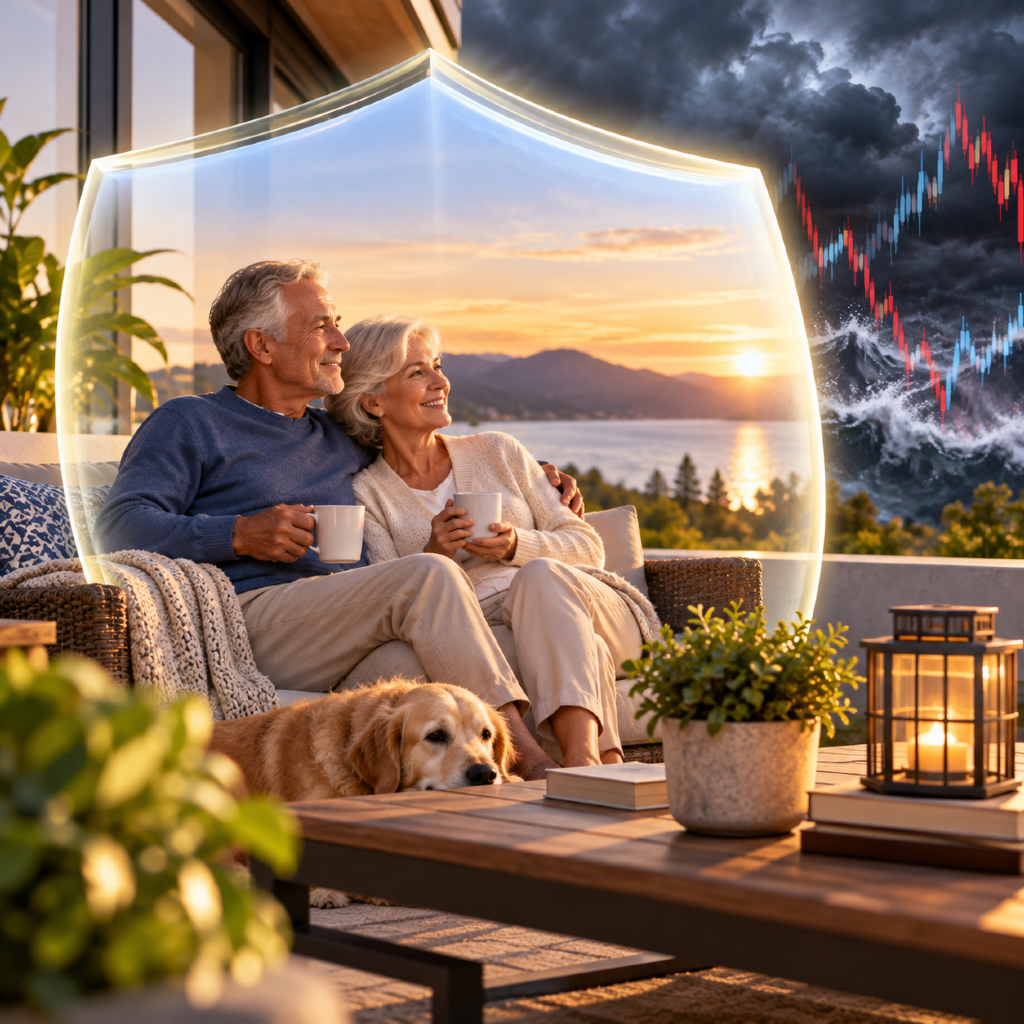
A volatility buffer is a resource set aside to provide income when the markets are down. Instead of selling investments at a loss, you can draw from this buffer. By doing so, you avoid realizing losses during tough market periods, giving your core portfolio time to recover when conditions improve. The ultimate goal: support steady income and help preserve your retirement savings.
How Can Life Insurance Help Retirement Stability?
Life insurance as a safe-money resource
Certain types of life insurance—especially permanent coverage with cash value features—can serve as a stable resource in retirement. The cash value in a permanent policy is not directly exposed to market swings. This lets you access funds as needed, especially during periods of market downturn, to maintain your income flow.
When you’re no longer working, having a safe-money resource to turn to can relieve the pressure on your investments. Life insurance, when structured with retirement needs in mind, can supplement your income temporarily so you can avoid withdrawing from equity markets at the wrong time.
Case: Managing market downturns
Imagine a scenario where the stock market enters a slump just as you need money for living expenses. Rather than withdraw from your retirement portfolio early in the downturn, you use the accessible cash value in your life insurance policy. This move effectively acts as a volatility buffer, reducing the need to realize losses on your investments. Once the markets stabilize or recover, you can resume withdrawals from your investment accounts.
Why Consider Safe-Money Strategies?
Risks of sequence of returns
One of the biggest dangers facing retirees is the sequence of returns risk. This refers to the risk of experiencing poor investment returns early in retirement, when you’re also drawing from your portfolio. Early losses combined with withdrawals can dramatically shrink your nest egg, even if average returns later are positive. The timing of returns matters much more when you’re living on your savings than when you’re still accumulating them.
The value of risk reduction
Safe-money strategies are designed to manage these risks. By using resources that are insulated from market volatility—like permanent life insurance cash value—you reduce the pressure on your primary investments. The ability to pause withdrawals from volatile assets during downturns can help you weather challenging periods without derailing your long-term plans. In retirement planning, risk reduction isn’t about perfect certainty, but about creating a smoother, more reliable financial journey.
Key Benefits of Volatility Buffering
Supporting steady income flows
The major advantage of adopting a volatility buffer is greater consistency in your retirement income. Resources like the cash value of a life insurance policy can be tapped when needed, meaning you aren’t forced to sell stocks or mutual funds during a market decline. This helps reduce the risk of outliving your savings and allows you to better plan for monthly expenses without worry.
Offering psychological confidence
Financial uncertainty can be stressful, especially in retirement. Knowing you have a buffer helps reduce anxiety when markets are turbulent. This psychological confidence can empower you to stay committed to your long-term investing strategy, rather than making hasty decisions out of fear. When your withdrawal plan incorporates both market-based and safe-money resources, you have greater control over how—and when—you take income.
Is Life Insurance Right for All Retirees?
Factors to evaluate
While the volatility buffer strategy is appealing, it may not be suitable for everyone. Ask yourself:
- Do you already own permanent life insurance with significant cash value?
- Are you willing and able to commit to the costs and complexity of a new policy?
- What is your overall health and insurability?
- How do your existing income sources (Social Security, pensions, annuities) fit into your withdrawal plan?
Careful evaluation is essential, especially since permanent life insurance is a long-term commitment and can involve fees or conditions for accessing cash value. It’s wise to review your full financial picture and consider guidance from a qualified professional.
Who may benefit most?
Retirees or pre-retirees who value flexibility, are concerned about market swings, or want to leave a legacy for heirs may find this strategy particularly helpful. Those with higher net worth or those who already own a permanent life insurance policy may also benefit from using it as a stable backup income resource during market downturns. Ultimately, each situation is unique—what works for one person may not for another.