Key Takeaways
- Target-date funds can help automate risk management but come with inherent limitations.
- Understanding your risk tolerance and seeking guidance can lead to smarter retirement decisions.
Many near-retirees worry that market downturns will impact their savings—are target-date funds a shield against risk? You’re not alone if you are looking for ways to protect your retirement nest egg from unexpected setbacks. Let’s explore how target-date funds (TDFs) work, their strengths, and their drawbacks as you seek stable, long-term financial security.
What Are Target-Date Funds?
Definition and core features
Target-date funds are a type of mutual fund or collective investment that simplifies your retirement investing. They’re designed to match a specific retirement date, typically found in the name (such as “Target Retirement 2035 Fund”). You invest by picking the fund with the date closest to when you plan to retire.
Core features include:
- Automatic asset mix adjustment: The fund manages a blend of stocks, bonds, and other assets for you.
- Lifecycle focus: The investment strategy evolves over time to reflect your journey toward—and through—retirement.
- Hands-off management: Once you invest, the fund’s managers take care of rebalancing and allocation changes.
How do they adjust over time?
As your target retirement year approaches, the fund gradually shifts from riskier, growth-oriented investments like stocks to more conservative holdings such as bonds and cash. This process, known as the “glide path,” aims to balance potential growth in your early years with more stability as retirement nears.
Why Consider Risk in Retirement Planning?
Understanding market risk for retirees
Risk is an ever-present part of investing. For those approaching retirement, market risk—the chance that your savings will lose value due to market downturns—becomes especially important. As you get closer to relying on those funds for income, large swings in value can be harder to recover from.
Challenges in preserving long-term savings
Long-term savings need to last—sometimes 20 years or more through retirement. The challenge is to grow your nest egg while guarding against sequence-of-returns risk (the risk of poor returns right as withdrawals begin) and inflation, all while avoiding severe downturn losses. That’s why protective strategies are crucial for retirement planning.
How Do Target-Date Funds Manage Risk?
Automatic rebalancing explained
One of the signature benefits of target-date funds is automatic rebalancing. As market conditions change, the fund regularly adjusts your portfolio mix to stay aligned with its glide path. For example, if stocks surge and grow beyond the fund’s current target allocation, the fund will sell some stock holdings to reduce risk—keeping your asset mix in check without you having to act.
Role of diversification strategies
Target-date funds typically invest in many asset classes, including domestic and international stocks, bonds, and sometimes real assets. This diversification helps spread risk, so your savings aren’t overly exposed to one sector or market. The goal is to cushion the impact of a downturn in any one area, promoting steadier growth and reducing the potential for large losses as you approach retirement.
Can Target-Date Funds Really Offer Protection?
Risk mitigation: strengths and limits
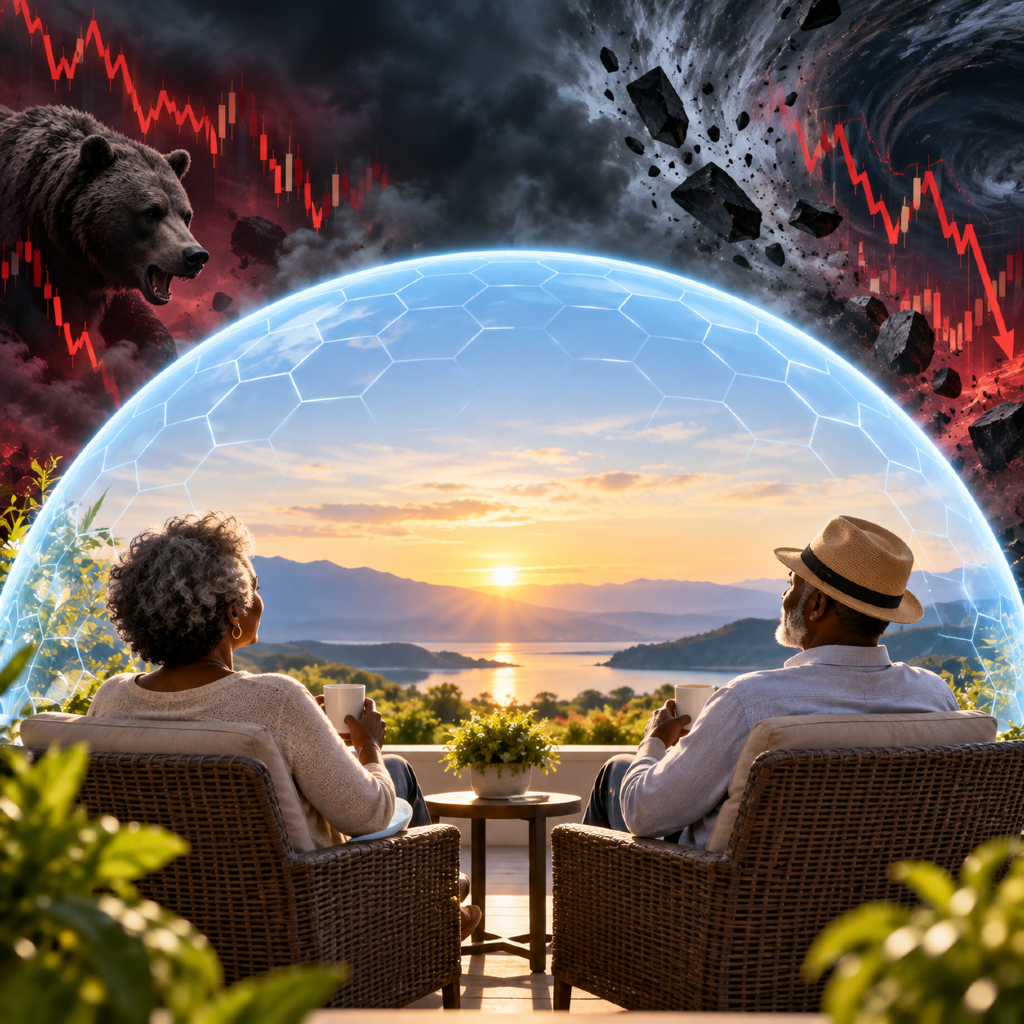
While target-date funds excel at automating complex portfolio management and gradually reducing exposure to risk, they do not eliminate market risk. The shifting allocation can help soften the blow of market turbulence, but your savings can still go down, especially during sharp market declines. TDFs provide a disciplined, rules-based approach to portfolio adjustment, which can benefit investors who prefer a “set it and forget it” strategy.
Market downturn scenarios
During major market downturns, such as the global financial crisis or more recent volatility, target-date funds have still lost value—though often less than more aggressive portfolios. The degree of loss depends on how close you are to your target retirement date (older funds, being more conservative, generally fare better) and the fund manager’s underlying investment choices. It’s important to understand that while these funds aim to manage risk, they cannot fully protect your portfolio from every market event.
What Are the Drawbacks of Target-Date Funds?
Potential risks and fees
Target-date funds come with features, but also drawbacks worth considering:
- Market risk remains: Your savings are still subject to moves in the stock and bond markets.
- Fees: While some funds have low management costs, others may charge higher fees that can eat into long-term returns—especially when layered on top of the underlying investments.
- Glide path variations: Not all TDFs follow the same risk-reduction path, and outcomes can differ significantly between fund providers.
One-size-fits-all approach limitations
A target-date fund applies a general risk-reduction formula meant for a broad audience—not your personal situation. If you have unique needs, health concerns, or preferences for income, you might find the fund’s standardized mix doesn’t fully align with your goals. This lack of customization is a major limitation, especially for those seeking more tailored risk management.
Are There Safer Alternatives Available?
Other principal protection strategies
Depending on your risk tolerance, you might consider other strategies for protecting your retirement savings. Options include conservative income funds, laddered bonds, certificates of deposit, or specific principal protection products. Each approach brings a different level of security and trade-off between safety and potential return.
Blending options for risk management
Some individuals use a combination of strategies, pairing target-date funds with individual bond ladders, cash reserves, or insured solutions to add extra stability. Blending approaches can help offset the unique risks of any single strategy, offering greater peace of mind.
How Can You Decide If They’re Right for You?
Questions to ask before investing
Ask yourself the following before choosing a target-date fund:
- How comfortable are you with market fluctuations and the possibility of loss?
- Does the fund’s glide path match your desired level of risk as you near retirement?
- Are you aware of all fees and how they impact your bottom line?
- Do you have other income streams or savings to supplement your retirement plan?
Importance of professional guidance
A financial professional can help you understand how target-date funds fit into the bigger picture of your retirement plan. They can assist in evaluating whether these funds align with your goals or if another approach might better address your specific needs. Professional guidance brings a deeper perspective on risk management and long-term security.