Key Takeaways
- Balancing safety and growth in TSP requires active risk management and a clear understanding of available protection options.
- Regular review, strategic diversification, and ongoing education help shield your retirement savings from unnecessary risks.
Many near-retirees worry their TSP savings aren’t fully protected—let’s explore practical approaches to safer retirement allocations. Learning to manage risk in TSP accounts can empower you to secure your future with more confidence and clarity.
What Is Safe Money in TSP?
Core concepts of safe-money strategies
Safe money strategies focus on preservation—stable ways to protect your retirement savings from major losses, especially during times of market volatility. These approaches help you avoid significant erosion of your nest egg, while still allowing for cautious long-term growth. In a retirement context, “safe money” means your principal is unlikely to fluctuate sharply in value, providing financial peace of mind.
How TSP fits into retirement planning
Your Thrift Savings Plan (TSP) is a foundational part of your retirement security. Federal employees, military personnel, and others use TSP to save and invest systematically for life after work. The TSP offers a range of funds, each with a unique balance of risk and protection. Learning which options emphasize safety, and how to combine them, is essential to building a stable, reliable retirement strategy.
Why Manage Risk in TSP Allocations?
Common risks in TSP investments
All investment plans include some element of risk. In TSP, risks include market volatility, economic downturns, and even inflation outpacing your returns. Some funds are more affected by these risks than others. Understanding these sources of uncertainty helps you select and adjust your allocations, safeguarding what you’ve built.
Consequences of unmanaged risk
If you leave risk unchecked in your TSP, your retirement savings may face sudden, unexpected losses—just when you need them most. For those approaching retirement, even a brief downturn can affect withdrawal rates and overall retirement security. Managing risk isn’t about avoiding growth altogether; it’s about steering your strategy to minimize the likelihood or impact of large setbacks.
How Can You Protect Your TSP?
Balancing growth and protection
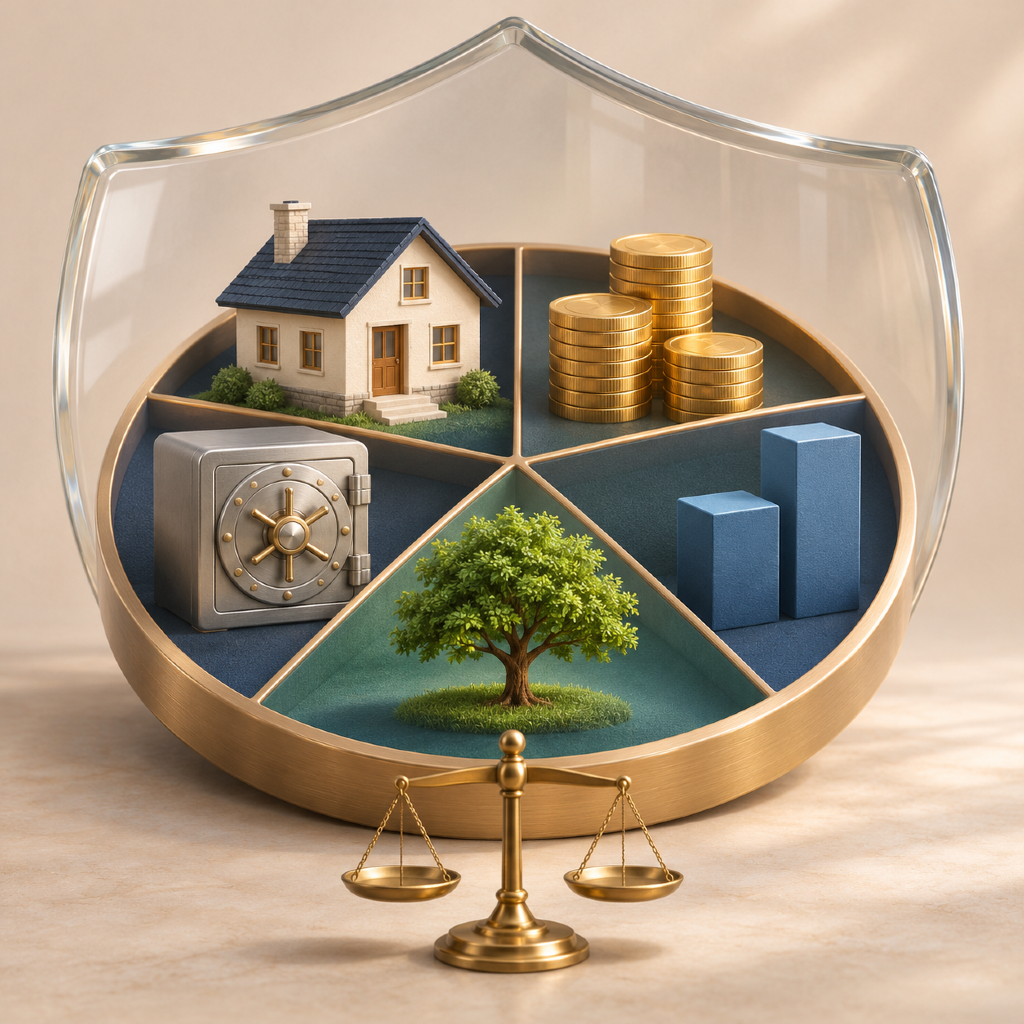
Protection within your TSP isn’t all-or-nothing. The goal is to strike a healthy balance: seek opportunities for conservative growth while holding a portion of your portfolio in less volatile, stable funds. This way, your money has room to grow, with a safety net to cushion unexpected swings.
Principal protection options within TSP
While no fund is entirely risk-free, some options emphasize preserving your original investment. For example, the TSP offers a government-backed fund—commonly recognized for its stability. This kind of fund doesn’t expose your balance to daily swings in the stock or bond markets, making it a popular choice for those prioritizing principal preservation. However, remember that a focus on protection may mean more modest long-term gains. Weighing these trade-offs is fundamental to your safe-money strategy.
What Risk Management Methods Work?
Diversification techniques explained
Diversification is one of your most effective tools for managing TSP risk. Instead of “putting all your eggs in one basket,” you spread your investments across multiple funds. Each fund responds differently to economic conditions. When some investments decline, others may hold steady or even grow, helping to stabilize your overall account value. This can mean including stock-oriented funds alongside safer, fixed-income ones—depending on your comfort and timeline.
Asset allocation strategies for protection
Asset allocation is the process of deciding how much of your TSP account to dedicate to each available fund. The right balance differs for everyone, but the core idea is simple: a mix of stable and growth-focused funds can help you weather turbulent markets without sacrificing all potential gains. Adjusting your allocation as you move closer to retirement—often called “glide path” adjustments—can further reduce risk as your need for stability increases.
Is Principal Protection Always the Priority?
When to prioritize stability over growth
There comes a time when protecting what you’ve earned takes precedence over maximizing growth. Typically, this is as you approach your planned retirement age, or when you know you’ll need to start withdrawing from your TSP. At this stage, a higher allocation to principal-protecting funds helps ensure recent gains are not easily lost to a sudden downturn.
Considering your risk tolerance and timeline
Everyone’s comfort with risk—and their intended timeline for needing funds—is unique. Use these factors as your compass. If market losses would significantly impact your plans or cause undue stress, it makes sense to shift toward safer allocations. If you’re younger, with years before retirement, accepting more market exposure may be appropriate; as retirement nears, gradually scaling back risk usually delivers greater peace of mind.
Common Mistakes with Safe Money Strategies
Overlooking inflation risk
Focusing solely on protecting your TSP principal can sometimes leave you exposed to inflation. If your returns barely keep pace with the rising cost of living, your purchasing power might actually shrink over time. While stability is crucial, consider how your allocations will perform after accounting for inflation—so your money continues to support your plans long into retirement.
Failing to revisit allocations regularly
A set-it-and-forget-it approach rarely aligns with your changing life circumstances. Economic environments shift, and your personal needs evolve. Reviewing your TSP allocations annually (or whenever your financial situation changes) helps ensure your safe-money strategy remains effective. Don’t hesitate to adjust as your retirement date approaches or your risk tolerance changes.
How to Start Improving Your TSP Safety
Steps to review your allocations
Begin by logging into your TSP account and reviewing where your contributions are currently directed. Compare your existing allocations to your personal risk comfort and retirement goals. Make small, incremental adjustments where needed—avoiding wholesale changes in response to short-term news or market swings. Document your reasoning each year to track your evolving strategy.
Seeking professional financial education
Ongoing financial education is one of the most reliable ways to protect your money. Reputable resources, webinars, and unbiased professionals can demystify complex topics and reveal safer approaches to managing your TSP. While this information is educational, reach out for professional advice if you’re unsure how your unique circumstances fit within these general principles.