Key Takeaways
- A protected income ladder strategy can provide steady, predictable retirement income while helping you manage market risk.
- Personalizing the ladder to your needs and regularly reviewing your plan are crucial for long-term success.
Most retirees say their top concern is running out of money—discover how the protected income ladder can address this worry. This guide introduces the income laddering concept, explains how it can help safeguard your financial future, and breaks down a real-life example for better understanding.
What Is a Protected Income Ladder?
Defining the income ladder approach
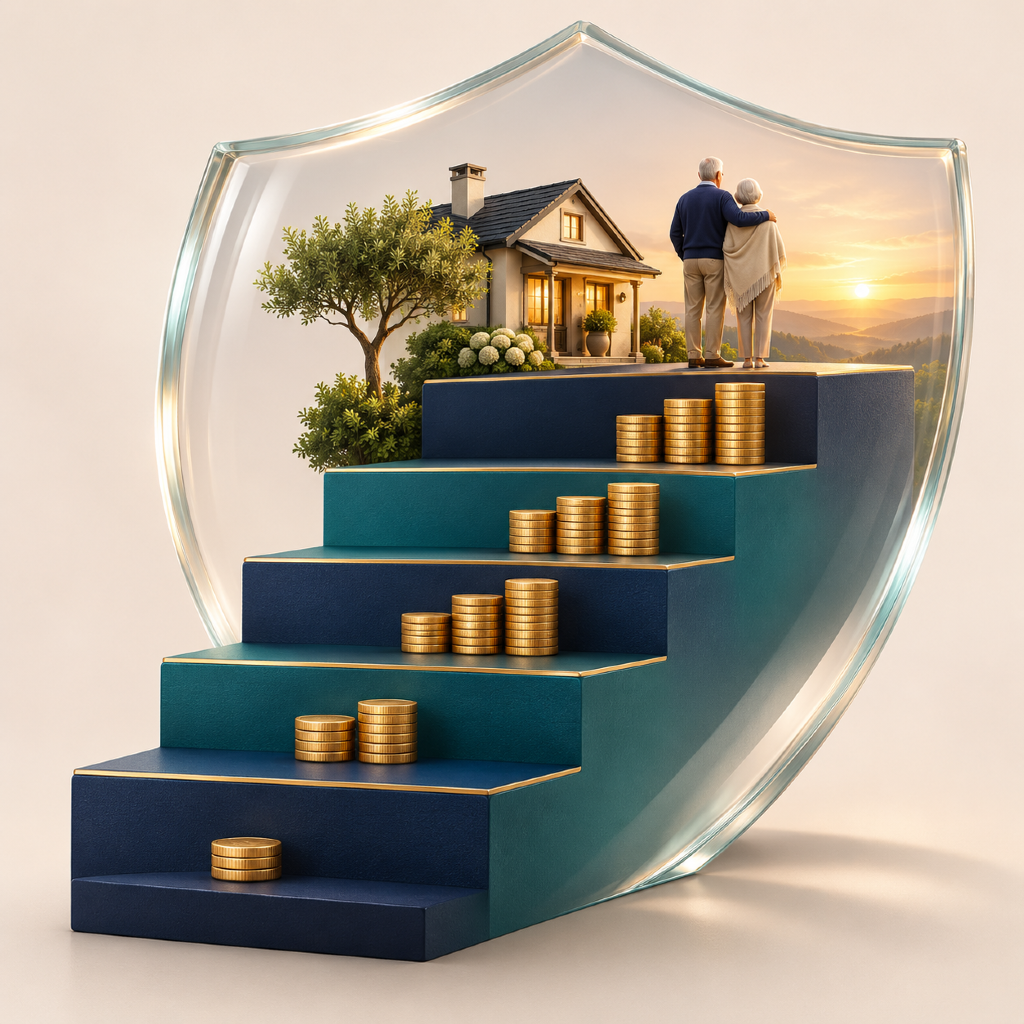
An income ladder is a retirement planning strategy that structures future income to arrive in scheduled steps—like rungs on a ladder—over the course of retirement. The approach aims to deliver a predictable income stream by spreading sources and timing, so you won’t have to depend on a single account or investment at any one time. Each “rung” is a separate pool of money or guaranteed payment scheduled to mature or begin at a set age.
How protected strategies differ from traditional methods
What makes a protected income ladder unique is the intentional use of solutions that focus on income protection, aiming to help shield some or all of your principal from market risk. While traditional retirement methods might rely solely on diversified investments that can rise or fall with the market, a protected strategy pairs those investments with income tools designed specifically for principal preservation and steady payouts. This protection-first mindset aims to reduce anxiety about unpredictable market swings in retirement.
Why Consider This Strategy for Retirement?
Addressing market uncertainty
No two years in the market are exactly alike. Retirees today face more questions than ever about sequence-of-returns risk—the chance that adverse market losses early in retirement could jeopardize lasting income. By allocating some assets to protected rungs as part of an income ladder, you can reduce exposure to unpredictable downturns and build financial confidence regardless of what the markets do next.
Aligning income with retirement needs
Your retirement spending typically changes over time. Early years might be more active and expensive, while later years could require different budgeting. An income ladder allows you to align incoming funds with your evolving needs. Because you plan the rungs in advance, you have greater clarity about how much will be available—and when—making it easier to match your spending rhythms without constantly worrying about the next downturn.
How Does the Income Ladder Work?
Step-by-step strategy overview
The protected income ladder relies on layering several time-based income sources—each activating at different points in your retirement timeline. Here’s a simple overview:
- Map out your desired retirement stages (e.g., every 5–10 years).
- Allocate a portion of your savings toward each stage, using a mix of protected and growth-oriented solutions that fit your risk comfort.
- Lock in protected rungs (such as defined income products or insured accounts) for your near-term and mid-term needs.
- Keep a portion in investments aimed at longer-term growth for rungs further down the ladder.
- As you reach each rung, funds become available for withdrawal, while the remaining rungs continue to mature for future years.
Building multiple income sources
A robust ladder combines diverse sources—think of Social Security, pension benefits (if available), fixed income tools, and other guaranteed payout accounts. Pair these with investments that balance risk and protection, such as conservative bond ladders or secure drawdown plans, to further reinforce the remaining rungs. The focus is on layering, not “betting it all” on a single solution.
What Are the Potential Drawbacks?
Limitations of laddering income
Like all strategies, protected income ladders aren’t perfect for every scenario. They may reduce your overall upside potential, since protected solutions often favor security over aggressive growth. In addition, laddering typically requires more upfront planning and diligence to keep funds properly segmented for each “rung.”
Risks and considerations to weigh
Costs, liquidity, and inflation are all critical factors. Protected strategies usually come with fees or product charges you’ll need to understand before committing. You may also lock up portions of your assets for specific timeframes, which could limit flexibility if unexpected expenses arise. Regular reviews will help account for changing needs and inflation adjustments.
Lessons from a Real-Life Case Study
Background and initial objectives
Consider Linda and Mark, a couple approaching retirement at ages 62 and 64. They were concerned about another market downturn just as they started spending their nest egg. Their top priorities were stable income and flexibility for health and travel in early retirement.
Implementation process
Working with a financial professional, they set up an income ladder by dividing savings into segments, each assigned to fund a 5–7 year period. The first rung relied on income from protected accounts designed to preserve principal. The surrounding rungs tapped into a mix of conservative bonds and long-term investments, scheduled to activate in later years. They also included survivor benefits and reviewed payout terms annually.
Long-term outcomes and adjustments
After the first ten years, Linda and Mark reported steady confidence as their income rungs paid out as planned. During a period of market volatility, their protected rungs kicked in as scheduled, allowing their remaining growth investments to recover. When their health expenses unexpectedly increased, they adjusted later rungs with help from their advisor, without disrupting essential spending needs.
Can This Strategy Fit Your Retirement Plan?
Factors to evaluate before starting
Before committing to any ladder strategy, consider your comfort with market risk, liquidity needs, and the balance between protection and growth objectives. Assess your income timeline, anticipated expenses, and whether you have adequate emergency funds set aside.
Questions to ask your financial professional
- How do protected rungs align with my personal risk tolerance and goals?
- What are the associated costs and commitments for each rung or account?
- How can the strategy be adjusted if my circumstances change?
- What processes are in place to review the ladder annually and keep it aligned with my evolving needs?
Reviewing these questions with a qualified financial professional helps ensure the ladder you build truly supports your unique retirement vision.