Key Takeaways
- Treasury ladders can improve income predictability while managing interest rate and reinvestment risk.
- Understanding each ladder structure’s benefits and limitations is vital to making an informed, risk-aware investment decision.
A treasury ladder can help you pursue steady income while aiming to preserve your principal. By comparing various treasury ladder strategies, you’ll see how each approach can strengthen income stability and address risk management—two crucial areas when planning for a secure financial future.
What Is a Treasury Ladder Strategy?
How treasury ladders work
A treasury ladder strategy involves buying several U.S. Treasury securities (such as Treasury bills, notes, or bonds) with different maturity dates. Instead of investing all your savings in a single security, you spread your investment across staggered maturities—perhaps ranging from 1 year to 10 years or even longer. As each security matures, you can withdraw the principal or reinvest it into a new Treasury at the longest end of the ladder, depending on your needs.
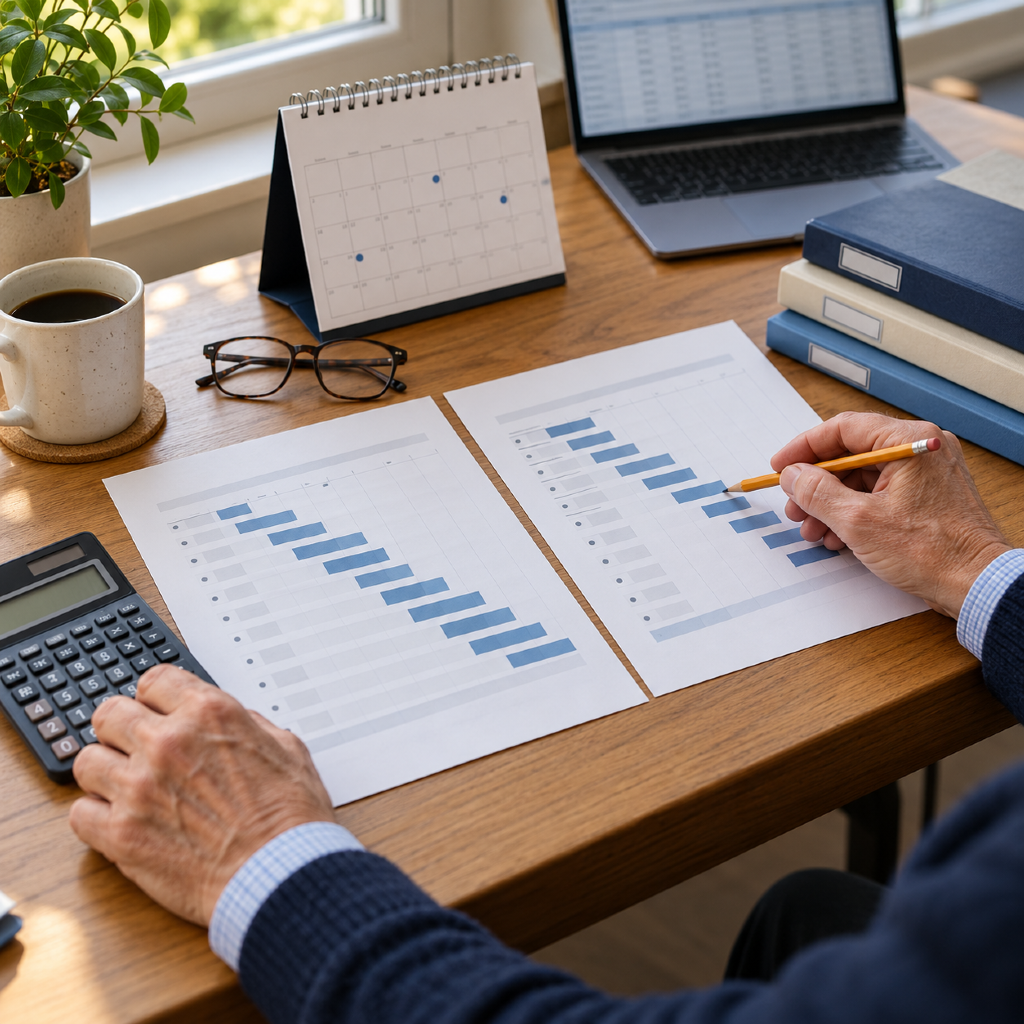
Say you build a five-year ladder: each year, one fifth of your invested securities matures. You can then reinvest the matured portion at current market rates. This cycle continues, diversifying how your money is exposed to various interest rate environments over time and helping protect against shifting rates.
Common reasons investors use ladders
Investors often use Treasury ladders to spread interest rate risk and improve cash-flow predictability. Ladders can add structure to an income plan—helping you receive regular, scheduled payments and keep your financial plan more organized. This approach often appeals to those seeking transparency, principal preservation, and minimal surprises from market fluctuations, especially in or approaching retirement.
How Does Income Stability Compare?
Income predictability explained
One of the main appeals of a treasury ladder is its potential to generate predictable income over a set period. Because the federal government issues U.S. Treasuries, many view them as a lower-risk asset for steady, scheduled interest payments and maturity proceeds. Spacing out maturities helps you plan when you’ll receive principal back, so you can manage withdrawals or reinvestments to match your financial needs.
With a well-constructed ladder, your payment stream can stay consistent, as interest from different rungs arrives at regular intervals. This supports both personal budgeting and cash flow stability, giving you confidence as you plan for essentials or future expenses.
Impact of different ladder structures
The composition of your ladder—such as the frequency and duration of each rung—can impact both the regularity and amount of income. Shorter ladders (with rungs maturing every year or two) may provide more flexibility for reinvesting in new interest rate environments. Longer ladders can lock in today’s rates for an extended period, which can be advantageous in certain interest rate climates.
Whereas a flat ladder (equal spacing across maturities) helps balance rate risk and cash flow, a “barbell” approach (using mostly short and long maturities) may offer a different tradeoff between liquidity, income stability, and exposure to interest rate changes.
Which Ladder Strategy Reduces Risk Most?
Risk types involved
Even with Treasuries, some key risks remain. Interest rate risk refers to the possibility that changing market rates reduce the value of your bonds before they mature. Reinvestment risk emerges if you must reinvest matured principal at lower rates. There’s also liquidity risk—not all bonds are easily sold for cash without possible market value loss, especially if held outside a ladder structure. For most investors, principal risk (the potential to lose your original investment) is considered very low with U.S. Treasuries held to maturity, given federal backing.
How ladders address these risks
Treasury ladders aim to manage these risks in several ways. By having bonds mature at different intervals, you reduce the risk of locking in at a single, possibly unfavorable, point in the interest rate cycle. If rates rise, only a portion of your portfolio matures, and you can reinvest it at the new, possibly higher, rates. If rates fall, some of your portfolio remains locked in at the older, higher rates.
This staggered approach helps smooth the impact of interest rate swings, making your portfolio more resilient to changing conditions. Liquidity risk is also reduced: because something is always maturing soon, you’re less likely to need to sell early and risk potential losses.
What Are the Main Benefits?
Managing interest rate changes
Treasury ladders can gently smooth the bumps that come with fluctuating interest rates. As rates change, only a portion of your holdings is affected at any one time. This process allows you to take advantage of higher rates when renewing maturing securities, while still benefiting from the stability of older rungs locked in at earlier, potentially higher rates.
Over time, this can minimize the guesswork in timing investments, making ladders a valuable tool if you’re seeking predictability and aiming to avoid market-timing decisions.
Leveraging liquidity for flexibility
Since a portion of your ladder matures regularly, you’ll have access to cash at set intervals—often annually or semi-annually, depending on your structure. This ongoing access provides greater flexibility to address unexpected expenses or take advantage of new opportunities as your needs change.
A well-structured ladder can help you keep money working for you, with the reassurance that a portion is never far from becoming available.
Are There Drawbacks to Treasury Ladders?
Liquidity considerations
Although ladders can improve access to cash as rungs mature, you may still face periods when funds are temporarily out of reach, especially if you need more liquidity than planned. Selling a Treasury before maturity can expose you to market price fluctuations—meaning you might get less back than you invested if rates have moved unfavorably.
Potential limitations in returns
While Treasuries are widely seen as a lower-risk asset, they generally offer lower interest rates than other securities. Building a ladder with only Treasuries may limit your return potential, especially when rates are low or when compared to other fixed-income investments. Balancing security and return is key—treasury ladders favor stability over chasing high yields.
How to Decide If a Ladder Fits You
Evaluating individual goals
Consider your financial goals before constructing a treasury ladder. If you prioritize steady income, manageable risk, and capital protection, this strategy may align well with your needs. However, it’s also important to assess your desire for liquidity, tolerance for interest rate changes, and overall investment time horizon. The ladder should fit comfortably alongside your other assets and income sources.
Discussing options with a professional
Before making significant changes to your financial plan, consider consulting a financial professional. An advisor can help you evaluate your options objectively and educationally—considering your unique needs and whether a treasury ladder complements your goals. This ensures you’re not just following a template, but building a strategy suited for your situation.
Frequently Asked Treasury Ladder Questions
Can ladders be customized?
Absolutely. Treasury ladders can be tailored for your preferred maturity range, frequency, and specific withdrawal needs. This adaptability is one reason ladders are a popular structure for many retirement and income planning strategies.
Is there a minimum investment needed?
There is no universal minimum, but each Treasury security has its own face-value increments. Check current requirements and work with a financial professional to build a ladder that fits your investment capacity and comfort level.