Key Takeaways
- Treasury ladders offer diversification and income stability in retirement.
- A laddered approach helps manage interest rate risk while focusing on principal protection.
Did you know that strategic use of Treasury ladders can help manage market risk and support steadier retirement plans, even in uncertain economic environments? Understanding how to implement a Treasury ladder can empower you to protect your savings and create more reliable income streams for retirement. Let’s explore what makes this approach a valuable component of safer financial planning.
What Is a Treasury Ladder?
Basic definition
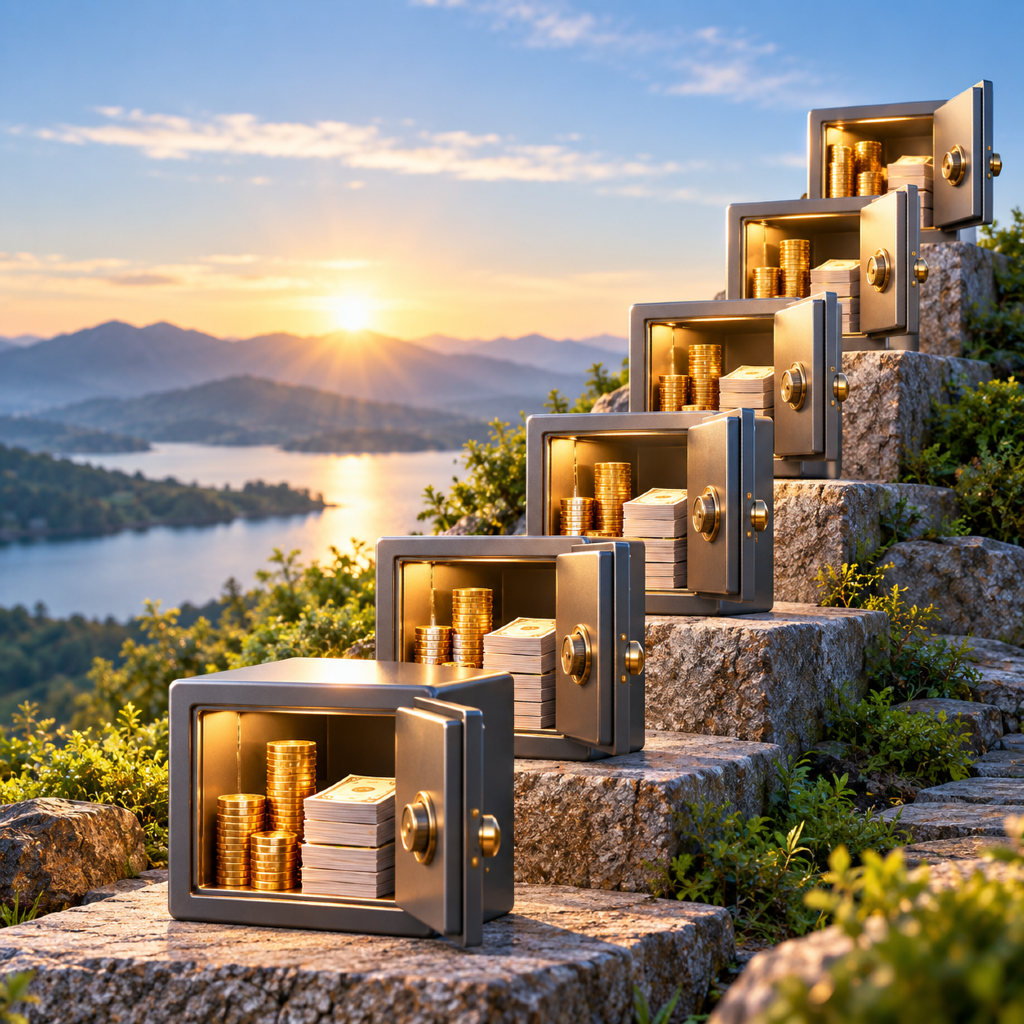
A Treasury ladder is a straightforward investment strategy involving the purchase of multiple U.S. Treasury securities with staggered maturity dates. Rather than placing all your funds in a single bond or certificate that matures at one time, you spread investments across different maturities—typically ranging from a few months to several years. This sequence, or “ladder,” provides access to your money at regular intervals as each security matures, while reinvesting proceeds helps maintain both liquidity and potential income.
How ladders work in practice
In practice, a Treasury ladder might include securities that mature every year over a five-year period. For example, each year, a portion of your investment becomes available, offering you choices: reinvest at then-current rates, use the funds for planned expenses, or adjust your strategy. By staggering your maturities, you reduce your exposure to sudden interest rate changes and help ensure that not all your funds are locked away for an extended period.
How Does a Ladder Reduce Risk?
Diversification of maturities
Laddering your Treasuries splits your capital among several bonds or bills, each maturing at a different point in time. This diversification of maturities means you are not wholly reliant on a single rate environment. When newer securities are purchased as older ones mature, your investment can adapt to shifting market rates rather than being anchored to one moment in time. This structure helps smooth income flow and offers flexibility to respond to economic changes.
Mitigating interest rate changes
One of the key benefits of a ladder is how it can alleviate the impact of interest rate movements. If rates rise, upcoming maturities allow you to reinvest at higher yields. If rates fall, you still benefit from higher-yielding bonds previously locked in, rather than having to reinvest all funds at lower rates. This layered approach is especially useful in retirement, as it limits the impact of market timing on your income.
Why Consider Treasuries in Retirement?
Safety and principal protection
U.S. Treasury securities are widely considered among the safest investments, backed by the full faith and credit of the U.S. government. They present a low level of credit risk, making them an attractive choice for individuals who prioritize principal protection. While all investments involve some level of risk, Treasuries are often favored for their stability and reliability, serving as a foundation for more secure retirement portfolios.
Income planning benefits
With predictable interest payments and clearly defined maturity dates, Treasuries simplify planning for future income needs. Creating a ladder allows you to match incoming cash flows with anticipated expenses, helping you cover living costs, health care, or other financial obligations in retirement. This predictability can be an important element when constructing long-term financial plans.
Step-by-Step: How to Build a Treasury Ladder
Step 1: Define your time horizon
Think about when you’ll need access to your funds. Are you planning for a short window of five years, or for the next decade and beyond? Knowing your expected retirement timeline helps determine the appropriate ladder structure.
Step 2: Choose ladder length
Decide how many rungs—or maturities—you’d like your ladder to have. Common ladders span between three to ten years, but you can select a duration that aligns with your comfort level and income needs. A longer ladder provides more diversification but may tie up funds for extended periods.
Step 3: Select Treasury maturities
Divide your investment into equal parts and allocate each part to a Treasury security maturing at different intervals. For example, if building a five-year ladder with $100,000, you might purchase $20,000 in bonds maturing each year for the next five years.
Step 4: Schedule purchases
It’s important to buy each rung of your ladder at the same time, ensuring that your maturities are evenly spaced. Many investors use direct purchase platforms, brokerages, or work with financial professionals to schedule and execute these purchases efficiently.
Step 5: Reinvest as needed
As each Treasury matures, you have options: take the proceeds as income, or reinvest in a new long-term rung to maintain the ladder. Reinvesting helps extend your ladder, keeping a steady cycle of maturing securities while adapting to current interest rates and your personal needs.
What Are the Key Risks to Know?
Interest rate movement risks
While laddering dampens the effect of rate changes, your portfolio’s value can still fluctuate if you sell securities before maturity. Laddering generally works best for those able to hold each security to term, as doing so locks in your principal—the full amount you initially invest.
Inflation considerations
Treasury securities pay a fixed rate, so if inflation rises faster than your coupon payments, your real (inflation-adjusted) returns could diminish over time. Some retirees consider mixing in inflation-protected securities or reevaluating ladder length and structure to help address this concern.
How Can Laddering Fit Diverse Needs?
Short-term versus long-term goals
A Treasury ladder can be structured to meet a wide range of planning objectives. Short-term ladders might help cover near-term living expenses, while longer-term ladders can provide stability over a decade or more. The flexibility of ladder creation means you can easily tailor it to evolving priorities.
Customizing for various retirement ages
Whether you’re 45 and planning ahead, or 70 and seeking preservation with liquidity, a Treasury ladder is customizable. Adjust the number of rungs, maturities, and reinvestment strategy to reflect your age, risk tolerance, and income requirements. This adaptability makes laddering relevant throughout your retirement journey.