Key Takeaways
- Cash buckets help prevent early depletion of retirement savings by managing withdrawals during volatile markets.
- Defending against sequence risk with cash buckets can support steady income and greater peace of mind in retirement.
Many retirees risk running out of their retirement nest egg too soon—especially in the face of unpredictable markets. By understanding sequence risk and the power of a cash bucket approach, you can better prepare and protect your retirement income for years to come.
What Is Sequence Risk in Retirement?
Definition and real-world implications
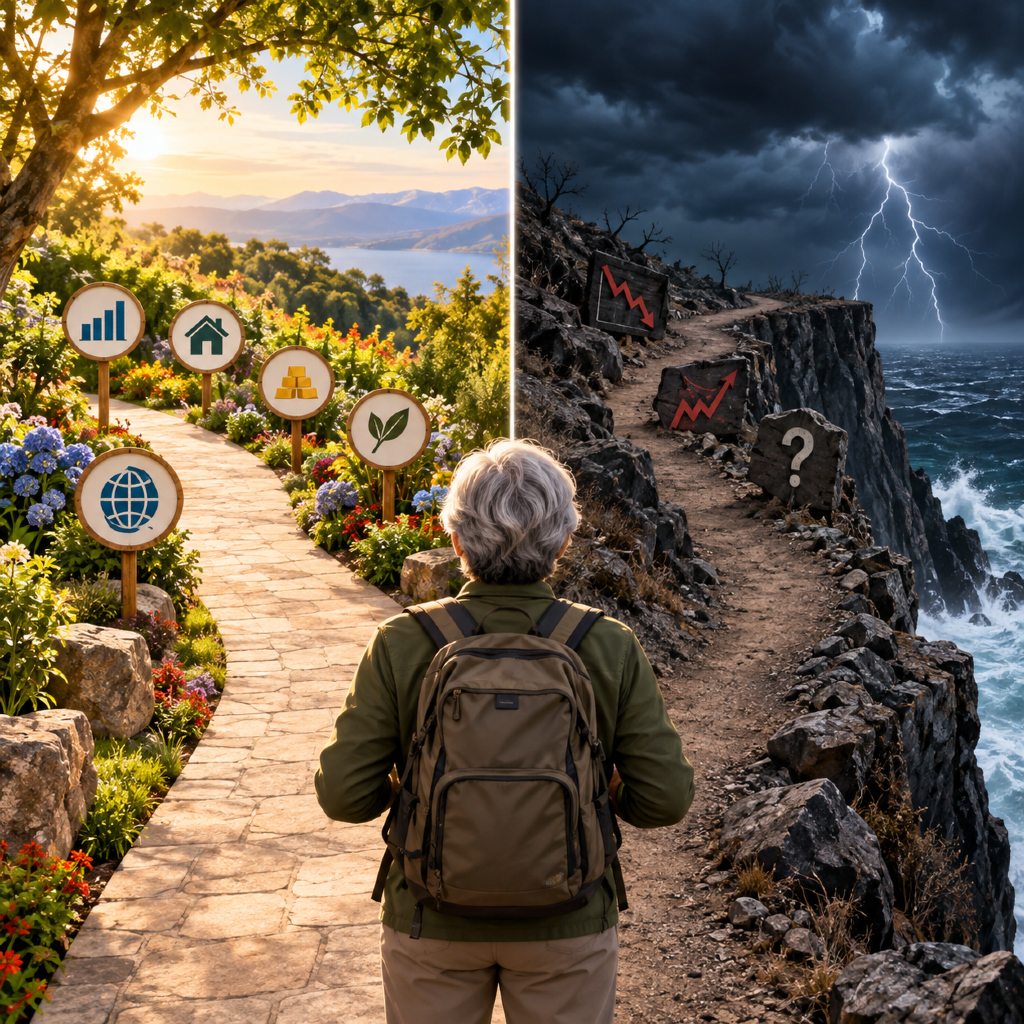
Sequence risk, also known as sequence-of-returns risk, is the danger that poor market performance early in your retirement could deplete your savings faster than expected. When you start withdrawing during a downturn, your asset base shrinks faster—and your investments have less time and fewer resources to recover.
Instead of focusing only on average long-term returns, sequence risk highlights a different concern: market losses relative to your withdrawals. Retirees can face drastically different outcomes based solely on the order in which good and bad years hit their portfolio.
Common scenarios impacting retirees
For example, if the first few years of your retirement coincide with a major market slump and you’re regularly withdrawing money to cover living expenses, your savings might not last as long as anticipated. Many retirees have seen their portfolios decline faster than planned, forcing tough decisions such as spending less, returning to work, or adjusting lifestyle expectations. Understanding sequence risk is crucial to developing a more robust income plan.
How Does the Cash Bucket Strategy Work?
Basic cash bucket structure
A cash bucket strategy segments your retirement assets into multiple “buckets,” each dedicated to different time horizons. Typically, the first bucket is made up of easily accessible cash or cash equivalents for immediate income needs (one to three years). Additional buckets are invested for mid-term and long-term growth, allowing those assets to weather market changes while the cash bucket supports near-term withdrawals.
Role in income planning
Using a bucket approach helps structure your income plan in a practical, systematic way. Instead of drawing directly from long-term market investments every year, you first spend from your cash bucket. This structure creates a buffer, helping you avoid taking investment losses during poor market conditions. As markets recover, you refill your cash bucket, maintaining a disciplined, sustainable approach to income.
Why Does Sequence Risk Matter Now?
Recent market volatility examples
The past few years have brought significant ups and downs, from rapid market recoveries to sudden downturns tied to global events. If you retired just before a major drop—as many did in early 2020 or late 2022—your sequence of returns could look much different than someone retiring during a period of market strength. Early losses, compounded by withdrawals, may sharply increase the chance of running short on savings.
Changes in retirement timing
Many people today are retiring in their early 60s while planning for life expectancies that might stretch into their 90s. That means your savings must last longer, often across shifting economic conditions. With traditional pensions less common and the cost of living rising, defending against sequence risk is more urgent than ever.
7 Ways Cash Buckets Defend Savings
1. Stabilizing near-term income needs
Your immediate living expenses are always covered from the cash bucket, insulating your day-to-day finances from sudden market drops. This means you can continue to meet essential expenses, regardless of what happens in the markets.
2. Minimizing withdrawals during downturns
When stock or bond markets are temporarily down, a cash bucket allows you to avoid selling investments at a loss to fund your spending. By pausing or reducing withdrawals from market-exposed funds, you safeguard your portfolio from compounding negative effects.
3. Allowing investments to recover
By tapping the cash reserve during volatile periods, your risk-based investments—such as stocks or bonds—have time to recover after a downturn. This increases the chance that the long-term portion of your portfolio can rebound and keep supporting your goals.
4. Reducing emotional decision-making
Market swings can prompt emotional reactions and hasty decisions, like selling assets at an inopportune moment. A reliable cash bucket encourages calm, rational planning and helps you stick to your income strategy.
5. Supporting steady spending habits
Consistent income enables you to maintain your chosen lifestyle, even when markets are unpredictable. With a funded cash bucket, you’re less likely to drastically adjust your spending or worry about outliving your savings.
6. Helping manage longevity risk
Longevity risk—the chance of living much longer than average—can stretch resources thin. With cash buckets, you can pace withdrawals prudently and adapt your income plan as health care needs, the cost of living, or life circumstances change.
7. Enhancing overall retirement resilience
A cash bucket system protects against more than just financial uncertainty. It adds flexibility and confidence, allowing you to adapt, rebalance, and weather periods of change while staying focused on long-term retirement security.
Is a Cash Bucket Right for Every Retiree?
Considerations for different scenarios
While the cash bucket strategy provides a practical framework, it may not fit every retiree’s needs or goals. Factors such as your retirement timeline, investment risk tolerance, expected expenses, and access to other income sources all play a role in deciding whether to use a bucket system.
Cash buckets vs. other approaches
Alternatives include systematic withdrawal plans, annuity-based strategies, and more traditional income ladders using bonds. Each approach has its merits and limitations. Some retirees may prefer a hybrid setup that combines buckets with other diversification tactics. The key is to select a system you can understand, monitor, and maintain comfortably over time.
Key Steps to Implement a Cash Bucket
Setting up your buckets
Start by estimating your expected yearly expenses and emergency reserves. Allocate enough to cover two to three years in your cash bucket (using savings accounts or cash equivalents), then separate remaining funds into mid-term and long-term buckets for growth. Define clear rules for when and how you replenish the cash bucket from your investment accounts.
Monitoring and replenishing strategies
Regularly review your spending needs and rebalance your buckets—typically annually or after notable market shifts. If the market has performed well and your investment buckets have grown, you can move profits into cash. If markets are down, draw primarily from the cash bucket and wait for improvement before replenishing.